Workforce solutions provider ManpowerGroup (NYSE: MAN) met Wall Street’s revenue expectations in Q3 2026, with sales up 4.4% year on year to $4.84 billion. Its non-GAAP profit of $1.01 per share was in line with analysts’ consensus estimates.
Is now the time to buy ManpowerGroup? Find out by accessing our full research report, it’s free.
ManpowerGroup (MAN) Q3 2026 Highlights:
- Revenue: $4.84 billion vs analyst estimates of $4.84 billion (4.4% year-on-year growth, in line)
- EPS (GAAP): $1.01 vs analyst expectations of $1.01
- EPS (GAAP) guidance for Q4 2026 is $1.08 at the midpoint, beating analyst estimates by 11.3%
- Operating Margin: 1.7%, in line with the same quarter last year
- Free Cash Flow was -$16.8 million, down from $44.7 million in the same quarter last year
- Market Capitalization: $2.42 billion
Jonas Prising, ManpowerGroup Chair & CEO, said, "We delivered another quarter of consistent performance and strong execution as momentum continues across the organization. Our Manpower brand continues to lead the way, with notable share gains in the U.S. Our Experis and Talent Solutions brands experienced sequential revenue trend improvement which is encouraging. Our performance to date reinforces our confidence that 2026 is an inflection point for the business. At the same time, we continue to advance our transformation, expanding implementation beyond the U.S. and driving growth across our brands and regions while remaining on track to deliver on our cost savings target. Looking ahead, the combination of improving demand, strong execution, and continued progress on our transformation positions ManpowerGroup to drive sustainable, profitable growth."
Company Overview
Founded during the post-World War II economic boom when businesses needed temporary workers, ManpowerGroup (NYSE: MAN) connects millions of people to employment opportunities through its global network of staffing, recruitment, and workforce management services.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
With $18.92 billion in revenue over the past 12 months, ManpowerGroup is a behemoth in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices. However, its scale is a double-edged sword because it’s harder to find incremental growth when you’ve penetrated most of the market. For ManpowerGroup to boost its sales, it likely needs to adjust its prices, launch new offerings, or lean into foreign markets.
As you can see below, ManpowerGroup’s revenue declined by 1.5% per year over the last five years, a rough starting point for our analysis.
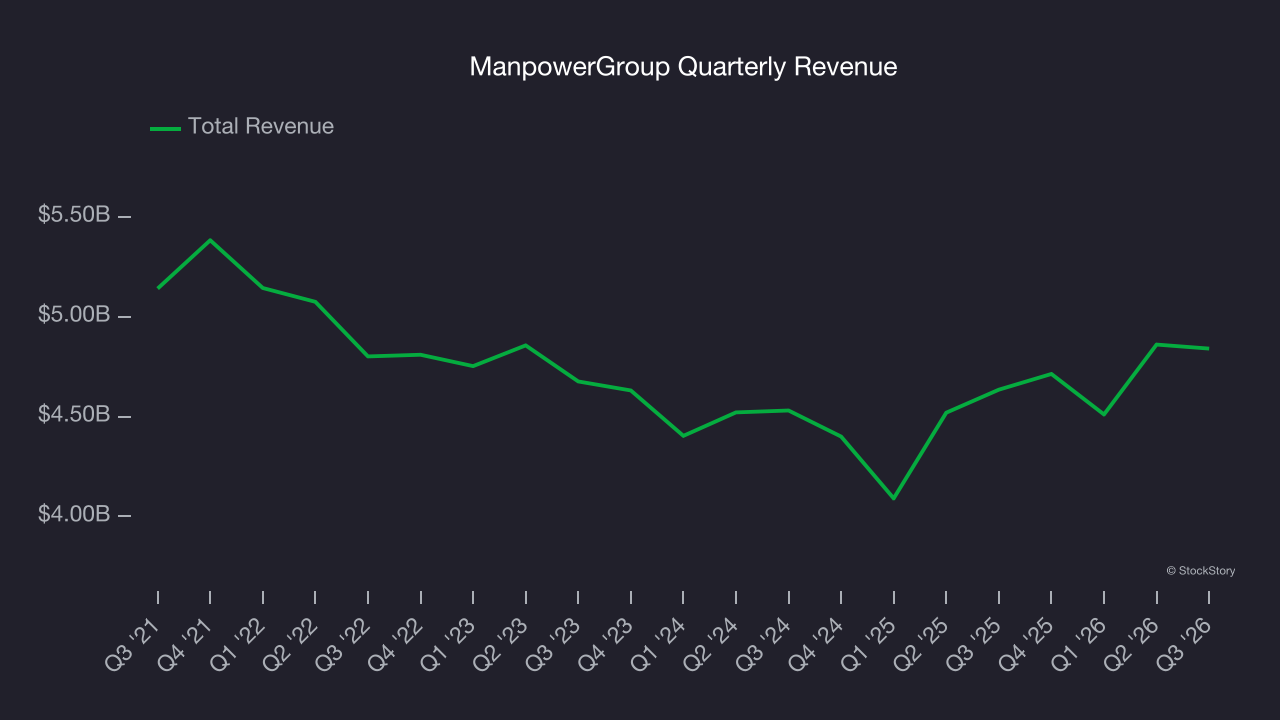
We at StockStory place the most emphasis on long-term growth, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. ManpowerGroup’s annualized revenue growth of 2.3% over the last two years is above its five-year trend, which is encouraging. 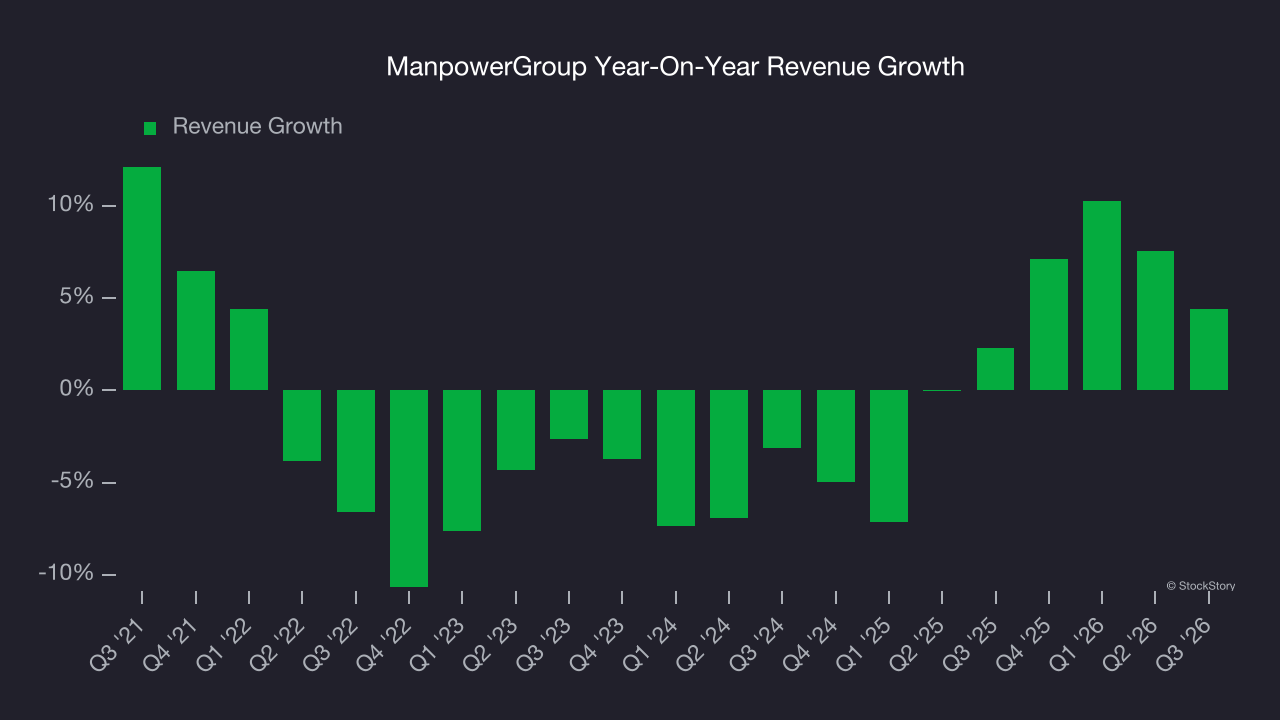
This quarter, ManpowerGroup grew its revenue by 4.4% year on year, and its $4.84 billion of revenue was in line with Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 3.3% over the next 12 months, similar to its two-year rate. Although this projection indicates its newer products and services will fuel better top-line performance, it is still below average for the sector.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Adjusted Operating Margin
ManpowerGroup was profitable over the last five years but held back by its large cost base. Its average adjusted operating margin of 2.4% was weak for a business services business.
Analyzing the trend in its profitability, ManpowerGroup’s adjusted operating margin decreased by 1.6 percentage points over the last five years. ManpowerGroup’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers.
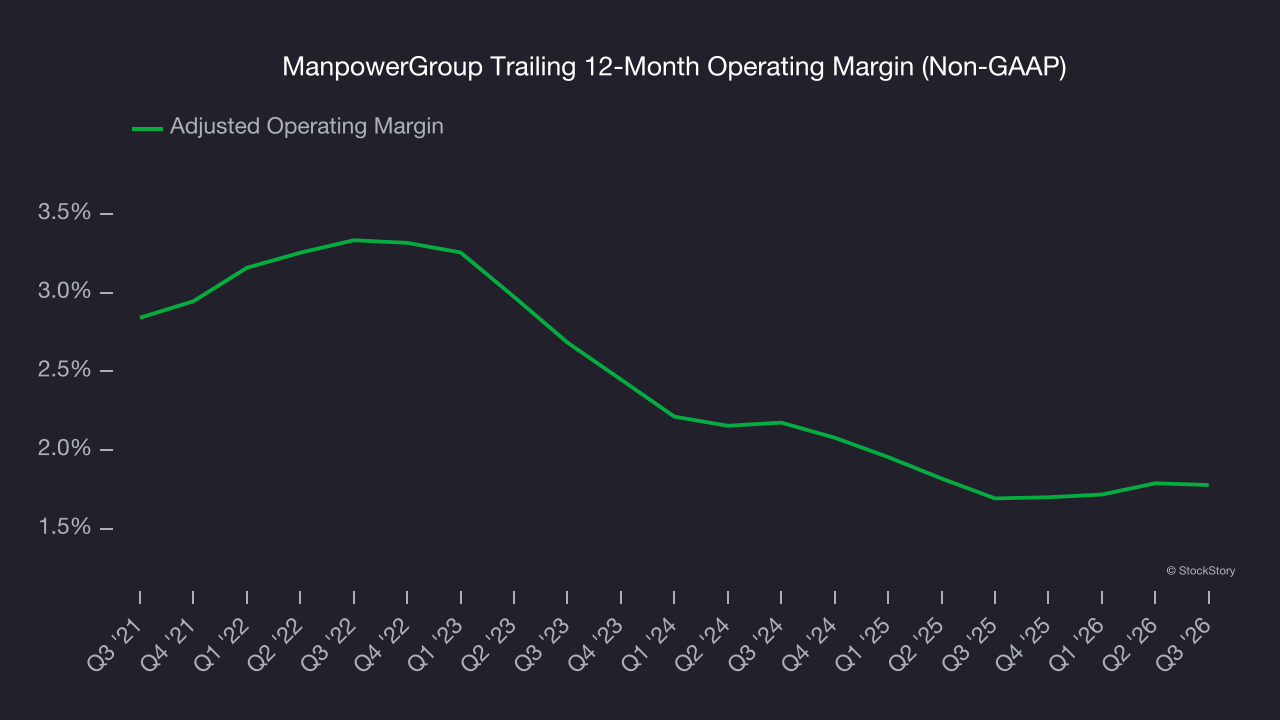
In Q3, ManpowerGroup generated an adjusted operating margin profit margin of 1.9%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Sadly for ManpowerGroup, its EPS declined by 16.5% annually over the last five years, more than its revenue. This tells us the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
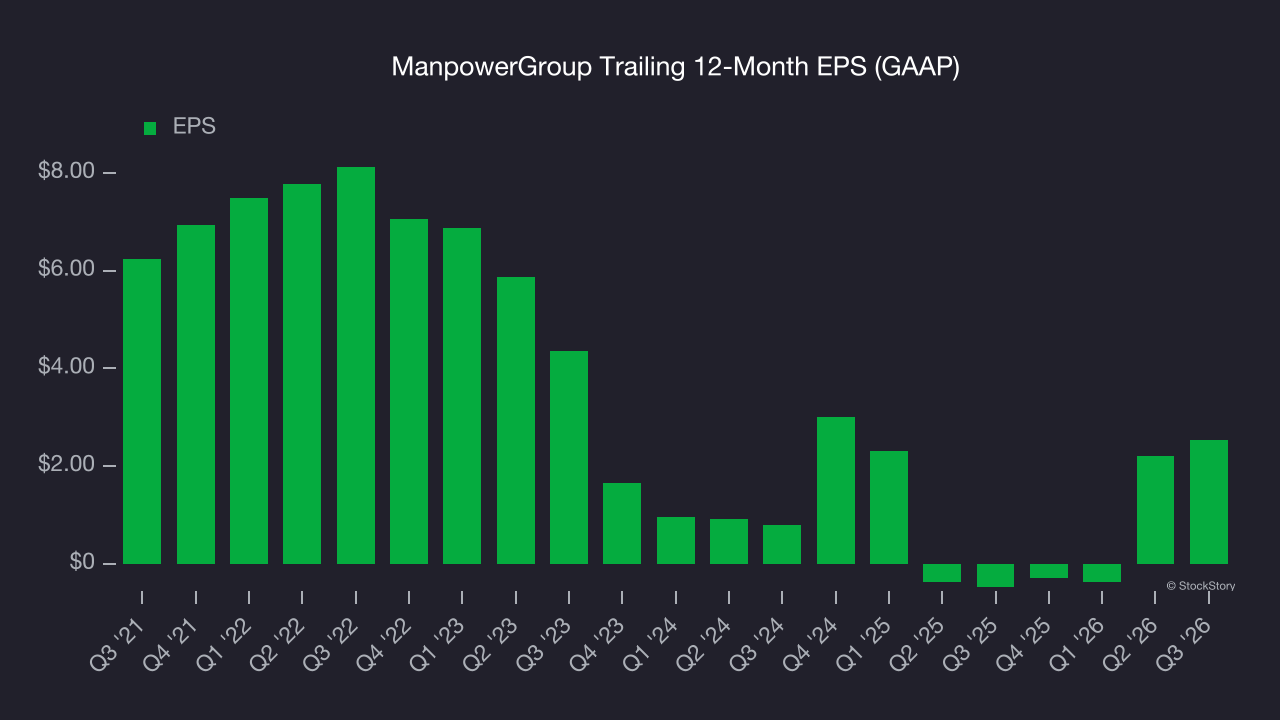
We can take a deeper look into ManpowerGroup’s earnings to better understand the drivers of its performance. As we mentioned earlier, ManpowerGroup’s adjusted operating margin was flat this quarter but declined by 1.6 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For ManpowerGroup, its two-year annual EPS growth of 78.9% was higher than its five-year trend. This acceleration made it one of the faster-growing business services companies in recent history.
In Q3, ManpowerGroup reported EPS of $0.71, up from $0.38 in the same quarter last year. Despite growing year on year, this print missed analysts’ estimates. Over the next 12 months, Wall Street expects ManpowerGroup’s full-year EPS to grow 70.4% from $2.54 to $4.32.
Key Takeaways from ManpowerGroup’s Q3 Results
We were impressed by ManpowerGroup's strong EPS guidance for next quarter vs. current expectations. Separately, the Company announced that the current CEO is stepping down January 1, 2027. The stock traded down 17.7% to $42.75 immediately after reporting.
So do we think ManpowerGroup is an attractive buy at the current price? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).