Medical technology company Intuitive Surgical (NASDAQ: ISRG) beat Wall Street’s revenue expectations in Q3 2026, with sales up 21.7% year on year to $3.05 billion. Its non-GAAP profit of $3 per share was 13.6% above analysts’ consensus estimates.
Is now the time to buy Intuitive Surgical? Find out by accessing our full research report, it’s free.
Intuitive Surgical (ISRG) Q3 2026 Highlights:
- Revenue: $3.05 billion vs analyst estimates of $2.90 billion (21.7% year-on-year growth, 5.3% beat)
- Adjusted EPS: $3 vs analyst estimates of $2.64 (13.6% beat)
- Operating Margin: 19.4%, down from 30.3% in the same quarter last year
- Market Capitalization: $153 billion
“Our strong performance this quarter was marked by broad-based adoption across our multi-port, single-port, and Ion platforms, with customers using our systems to perform, on average, over 10,000 procedures per day throughout the period,” said Dave Rosa, Intuitive CEO. “Looking ahead, we will remain focused on serving customers across geographies and sites of care, enabling them to deliver better patient care, outcomes, and experiences, reduce the total cost of care, and expand access to minimally invasive care.”
Company Overview
Pioneering minimally invasive surgery since its first da Vinci system was FDA-cleared in 2000, Intuitive Surgical (NASDAQ: ISRG) develops and manufactures robotic-assisted surgical systems that enable minimally invasive procedures across various medical specialties.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, Intuitive Surgical grew its sales at a solid 16.1% compounded annual growth rate. Its growth surpassed the average healthcare company and shows its offerings resonate with customers, a great starting point for our analysis.
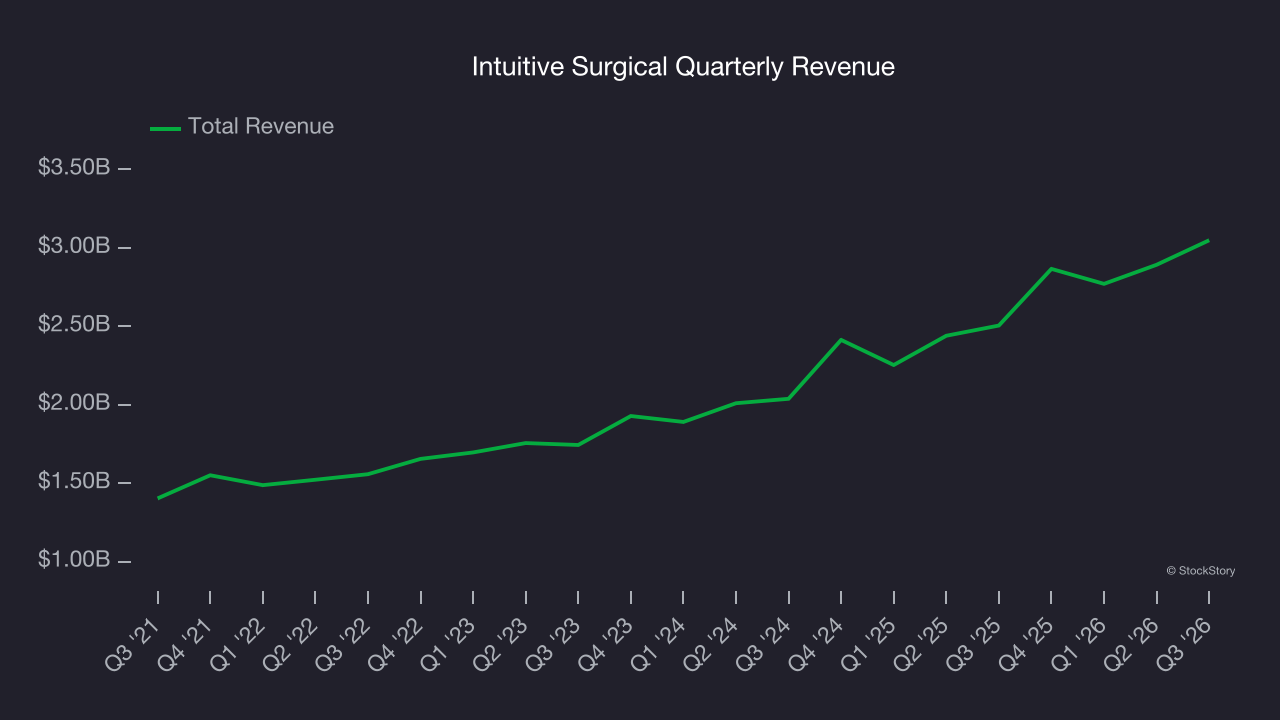
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. Intuitive Surgical’s annualized revenue growth of 21.3% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 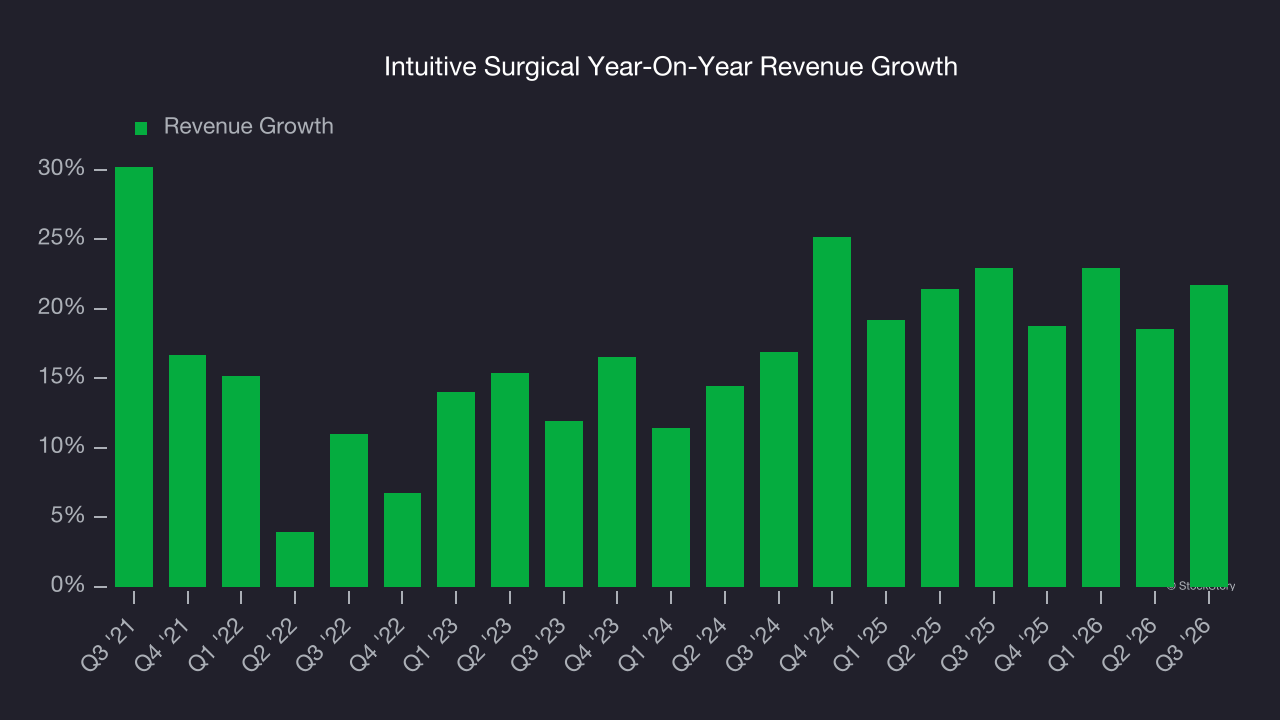
This quarter, Intuitive Surgical reported robust year-on-year revenue growth of 21.7%, and its $3.05 billion of revenue topped Wall Street estimates by 5.3%.
Looking ahead, sell-side analysts expect revenue to grow 10.5% over the next 12 months, a deceleration versus the last two years. We still think its growth trajectory is attractive given its scale and suggests the market is forecasting success for its products and services.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Adjusted Operating Margin
Adjusted operating margin is one of the best measures of profitability because it tells us how much money a company takes home after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
Intuitive Surgical’s adjusted operating margin has more or less stayed the same over the last 12 months , averaging 35.8% over the last five years. This profitability was elite for a healthcare business thanks to its efficient cost structure and economies of scale.
Analyzing the trend in its profitability, Intuitive Surgical’s adjusted operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
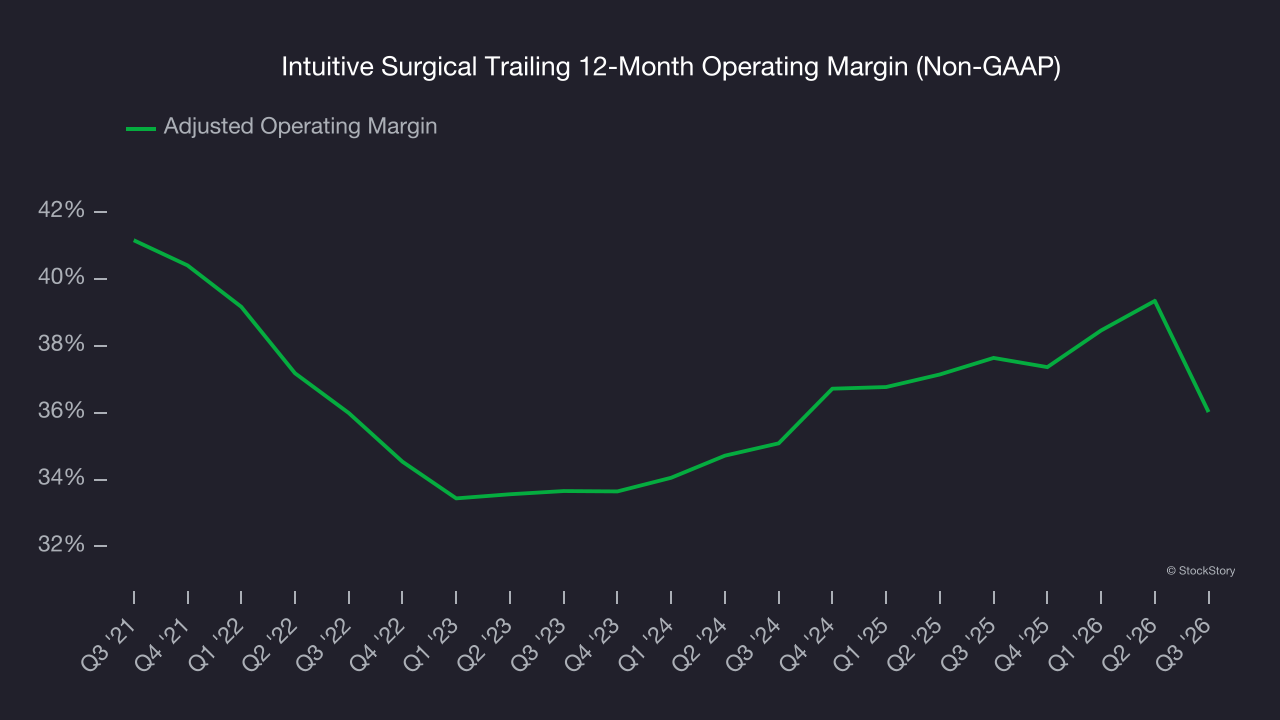
This quarter, Intuitive Surgical generated an adjusted operating margin profit margin of 26.4%, down 12.5 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Intuitive Surgical’s astounding 17.4% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
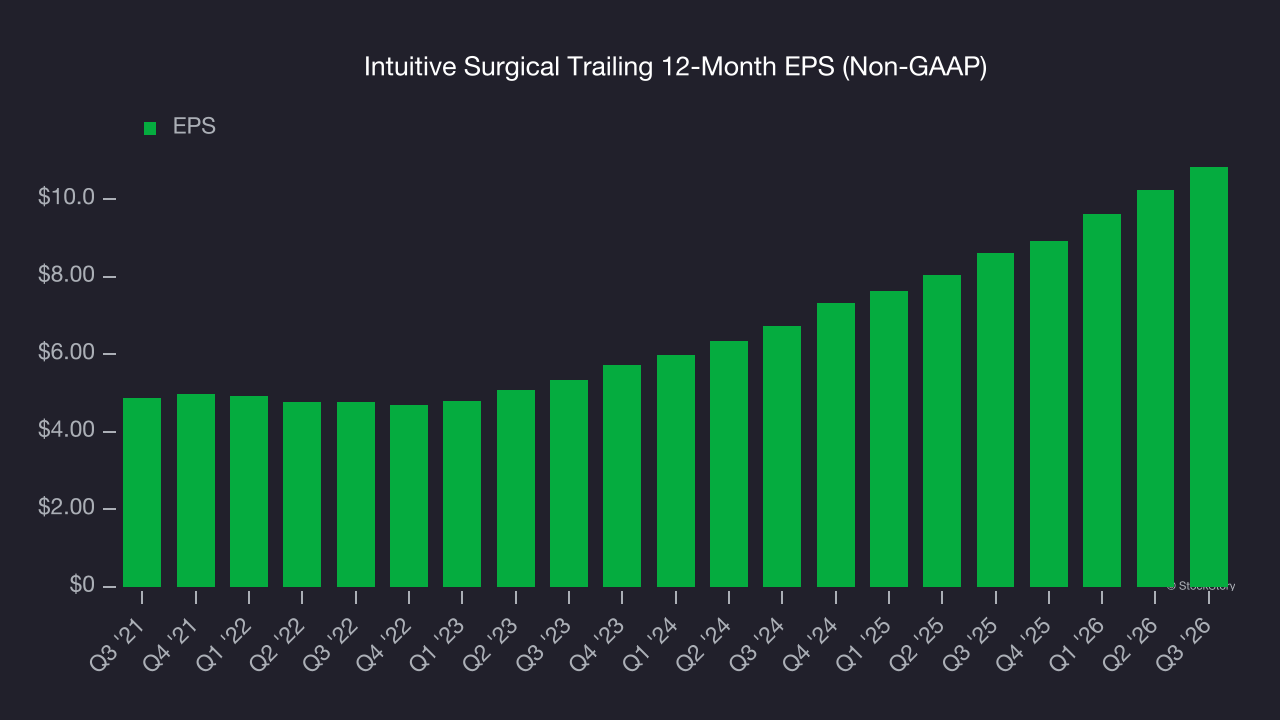
In Q3, Intuitive Surgical reported adjusted EPS of $3, up from $2.40 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects Intuitive Surgical’s full-year EPS to grow 7.9% from $10.83 to $11.68.
Key Takeaways from Intuitive Surgical’s Q3 Results
We were impressed by how significantly Intuitive Surgical blew past analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Zooming out, we think this quarter featured some important positives. The market seemed to be hoping for more, and the stock traded down 12.7% to $382.40 immediately following the results.
So do we think Intuitive Surgical is an attractive buy at the current price? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).