Digital small business lender Live Oak Bancshares (NYSE: LOB) reported Q3 2026 results topping the market’s revenue expectations, with sales up 18.3% year on year to $175.6 million. Its GAAP profit of $0.52 per share was 26.8% below analysts’ consensus estimates.
Is now the time to buy Live Oak Bancshares? Find out by accessing our full research report, it’s free.
Live Oak Bancshares (LOB) Q3 2026 highlights:
- Net Interest Income: $133 million vs analyst estimates of $130.8 million (15.2% year-on-year growth, 1.7% beat)
- Net Interest Margin: 3.3% vs analyst estimates of 3.3% (3 basis point miss)
- Revenue: $175.6 million vs analyst estimates of $166.4 million (18.3% year-on-year growth, 5.5% beat)
- Efficiency Ratio: 48.8% vs analyst estimates of 49.7% (86.7 basis point beat)
- EPS (GAAP): $0.52 vs analyst expectations of $0.71 (26.8% miss)
- Tangible Book Value per Share: $26.05 vs analyst estimates of $27.53 (8.4% year-on-year growth, 5.4% miss)
- Market Capitalization: $1.64 billion
“The fundamental story at Live Oak is that our franchise is getting stronger. Our operating leverage is improving, Live Oak Express continues to accelerate, and our deposit franchise is marching with gaining momentum,” said Live Oak Chairman and CEO James S. (Chip) Mahan III. “The earnings power of this business is expanding because revenue growth is meaningfully outpacing expenses, our loan origination engine is running strong, and our strategic initiatives are delivering results. This operating leverage momentum has aided in absorbing the elevated provision expense in the quarter, which primarily supported record loan growth while also our continued efforts to decisively act to address stress in our distillery-related portfolio. As I think about our operating earnings model, strong loan pipeline, and the possibilities that AI may unlock for both our customers and our employees, I am truly excited about Live Oak’s future.”
Company overview
Founded during the 2008 financial crisis with a vision to reimagine small business banking through technology, Live Oak Bancshares (NYSE: LOB) is a bank holding company that specializes in providing online banking services and SBA-guaranteed loans to small businesses across targeted industries nationwide.
Sales growth
From lending activities to service fees, most banks build their revenue model around two income sources. Interest rate spreads between loans and deposits create the first stream, with the second coming from charges on everything from basic bank accounts to complex investment banking transactions. Luckily, Live Oak Bancshares’s revenue grew at a solid 12.1% compounded annual growth rate over the last five years. Its growth beat the average banking company and shows its offerings resonate with customers.
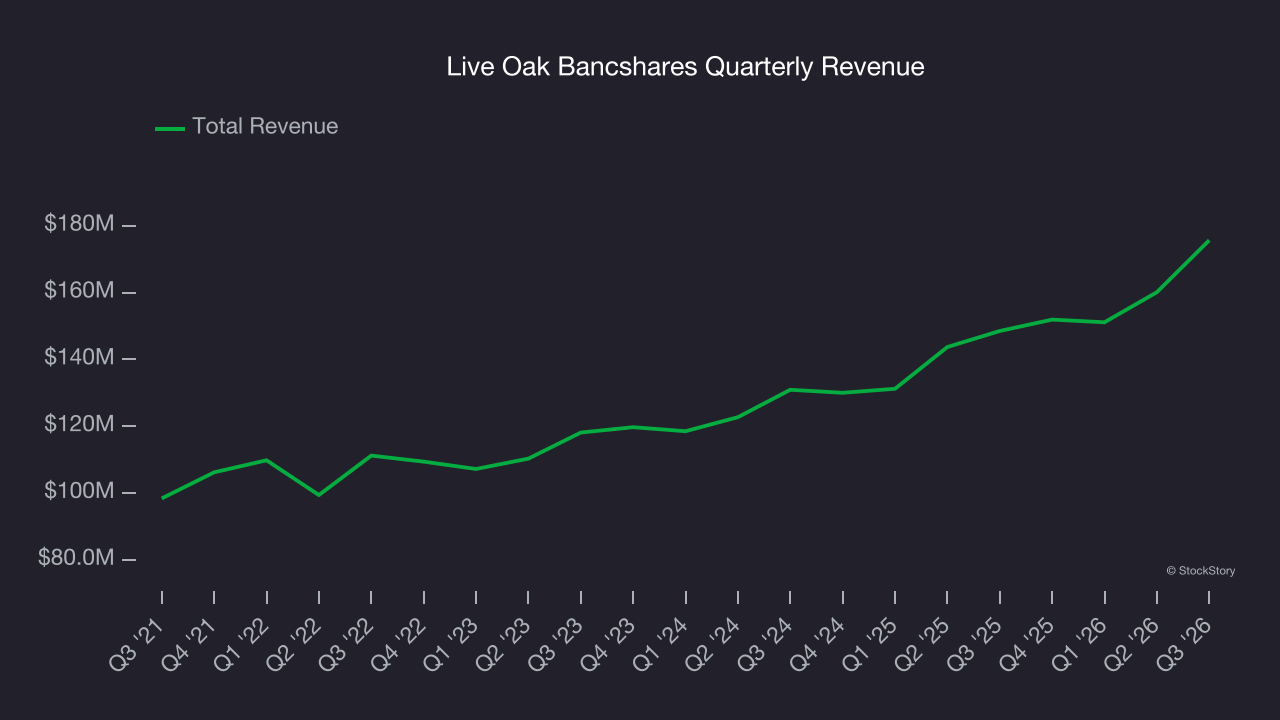
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. Live Oak Bancshares’s annualized revenue growth of 14% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 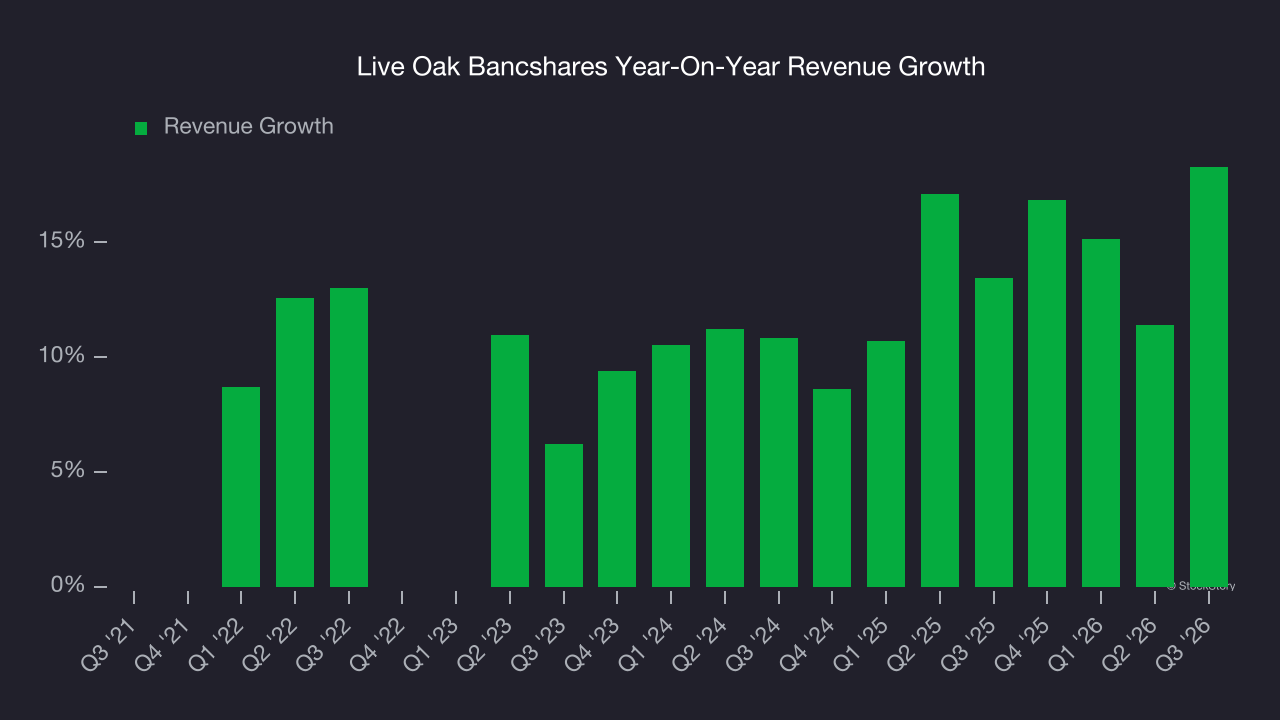 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Live Oak Bancshares reported year-on-year revenue growth of 18.3%, and its $175.6 million of revenue exceeded Wall Street’s estimates by 5.5%.
Net interest income made up 76.3% of the company’s total revenue during the last five years, meaning lending operations are Live Oak Bancshares’s largest source of revenue.
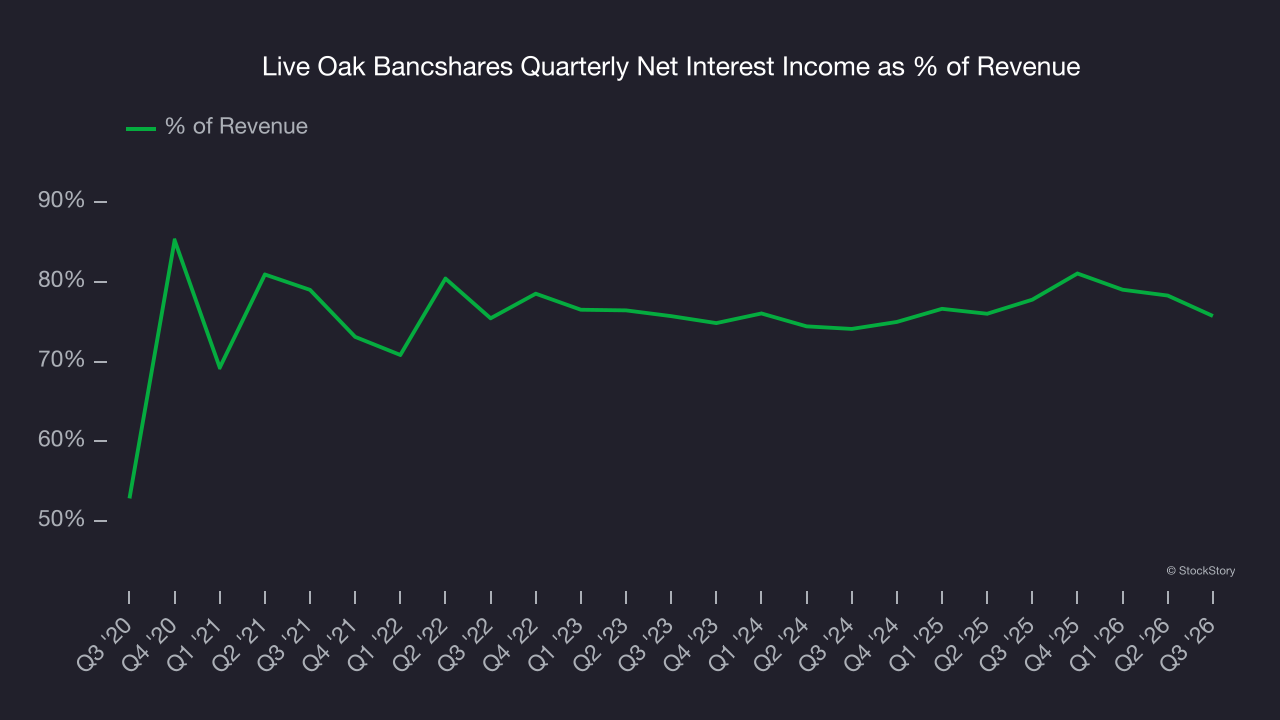
While banks generate revenue from multiple sources, investors view net interest income as the cornerstone - its predictable, recurring characteristics stand in sharp contrast to the volatility of non-interest income.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Tangible book value per share (TBVPS)
The balance sheet drives banking profitability since earnings flow from the spread between borrowing and lending rates. As such, valuations for these companies concentrate on capital strength and sustainable equity accumulation potential.
When analyzing banks, tangible book value per share (TBVPS) takes precedence over many other metrics. This measure isolates genuine per-share value by removing intangible assets of debatable liquidation worth. Traditional metrics like EPS are helpful but face distortion from M&A activity and loan loss accounting rules.
Live Oak Bancshares’s TBVPS grew at an incredible 10.4% annual clip over the last five years. However, TBVPS growth has recently decelerated a bit to 8% annual growth over the last two years (from $22.32 to $26.05 per share).
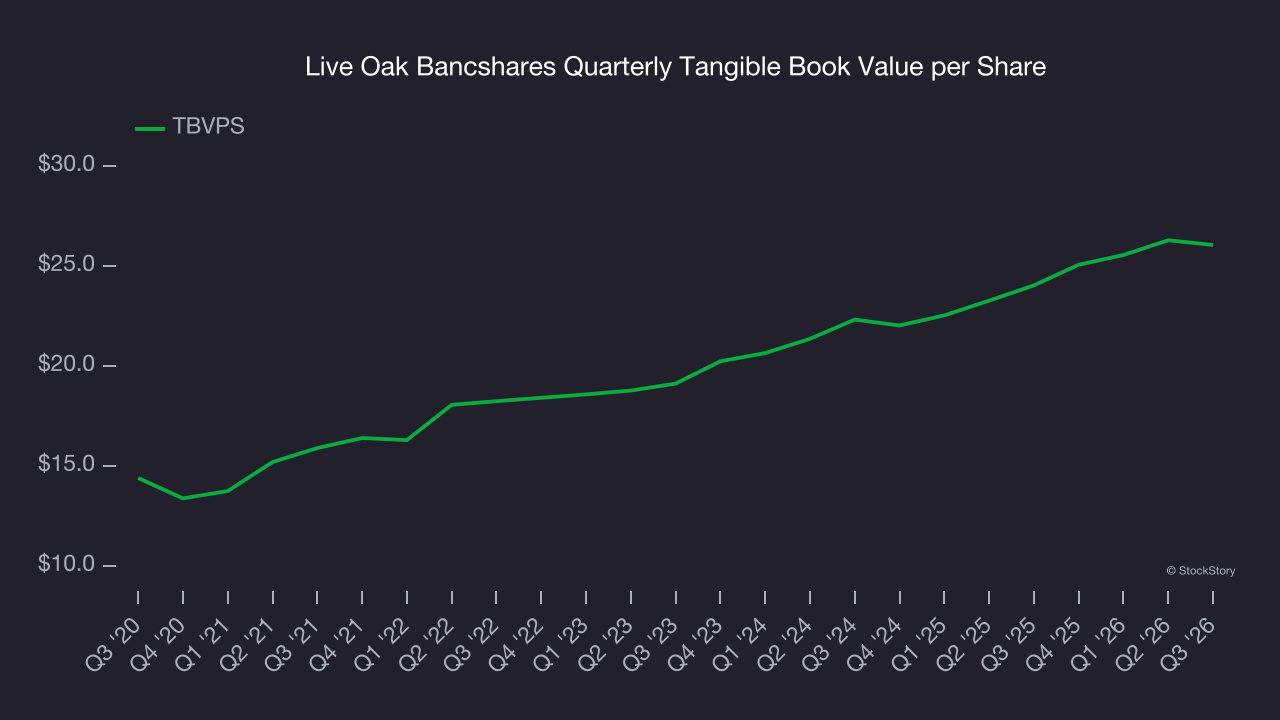
Over the next 12 months, Consensus estimates call for Live Oak Bancshares’s TBVPS to grow by 20.3% to $31.33, top-notch growth rate.
Key takeaways from Live Oak Bancshares’s Q3 results
We were impressed by how significantly Live Oak Bancshares blew past analysts’ revenue expectations this quarter. We were also happy its net interest income outperformed Wall Street’s estimates. On the other hand, its tangible book value per share missed and its EPS fell short of Wall Street’s estimates. Overall, this was a weaker quarter. The stock remained flat at $35.35 immediately after reporting.
So do we think Live Oak Bancshares is an attractive buy at the current price? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).