
Regional banking company 1st Source (NASDAQ: SRCE) beat Wall Street’s revenue expectations in Q3 2026, with sales up 6.7% year on year to $120.3 million. Its GAAP profit of $2.03 per share was 11.1% above analysts’ consensus estimates.
Is now the time to buy 1st Source? Find out by accessing our full research report, it’s free.
1st Source (SRCE) Q3 2026 highlights:
- Net Interest Income: $95.59 million vs analyst estimates of $94.24 million (7.7% year-on-year growth, 1.4% beat)
- Net Interest Margin: 4.3% vs analyst estimates of 4.2% (7.7 basis point beat)
- Revenue: $120.3 million vs analyst estimates of $118.2 million (6.7% year-on-year growth, 1.8% beat)
- Efficiency Ratio: 45.9% vs analyst estimates of 47.3% (139 basis point beat)
- EPS (GAAP): $2.03 vs analyst estimates of $1.83 (11.1% beat)
- Tangible Book Value per Share: $51.31 vs analyst estimates of $52.03 (8.8% year-on-year growth, 1.4% miss)
- Market Capitalization: $2.07 billion
Company overview
Tracing its roots back to 1863 during the Civil War era, 1st Source Corporation (NASDAQ: SRCE) is a regional bank holding company that provides commercial, consumer, specialty finance, and wealth management services across Indiana, Michigan, and Florida.
Sales growth
From lending activities to service fees, most banks build their revenue model around two income sources. Interest rate spreads between loans and deposits create the first stream, with the second coming from charges on everything from basic bank accounts to complex investment banking transactions. Over the last five years, 1st Source grew its revenue at a tepid 6.5% compounded annual growth rate. This wasn’t a great result compared to the rest of the banking sector, but there are still things to like about 1st Source.
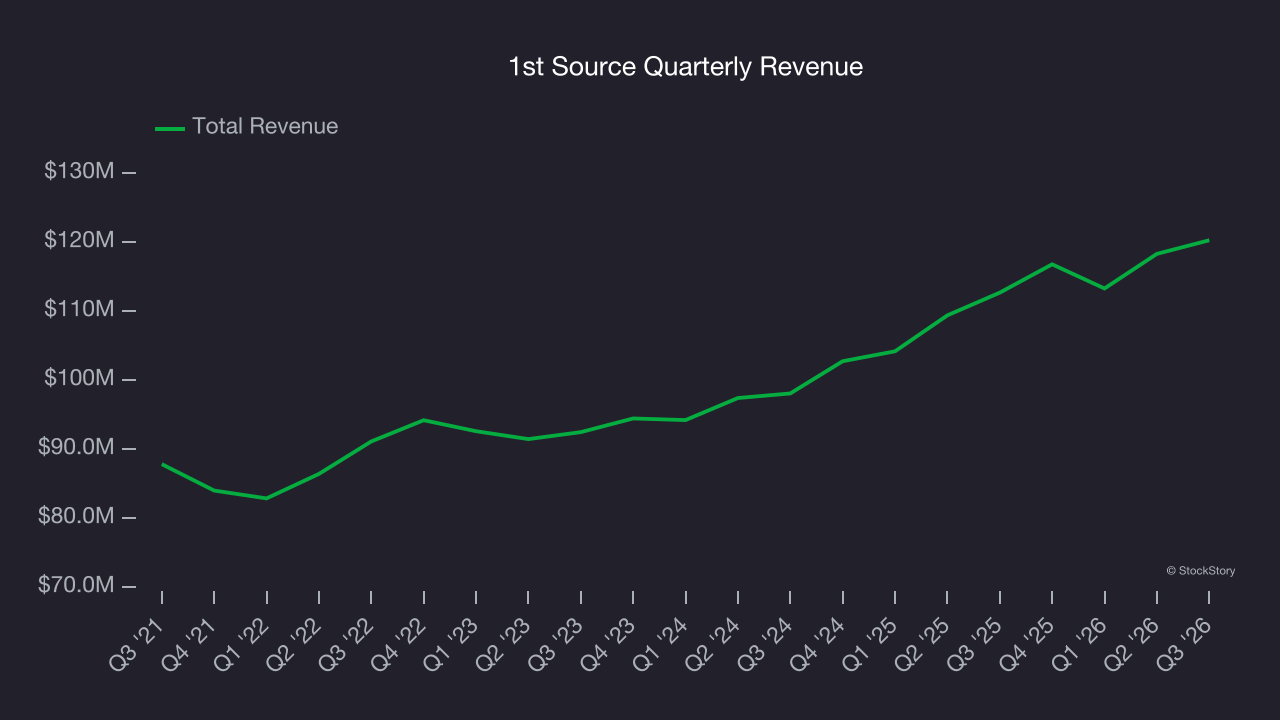
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. 1st Source’s annualized revenue growth of 10.5% over the last two years is above its five-year trend, suggesting some bright spots. 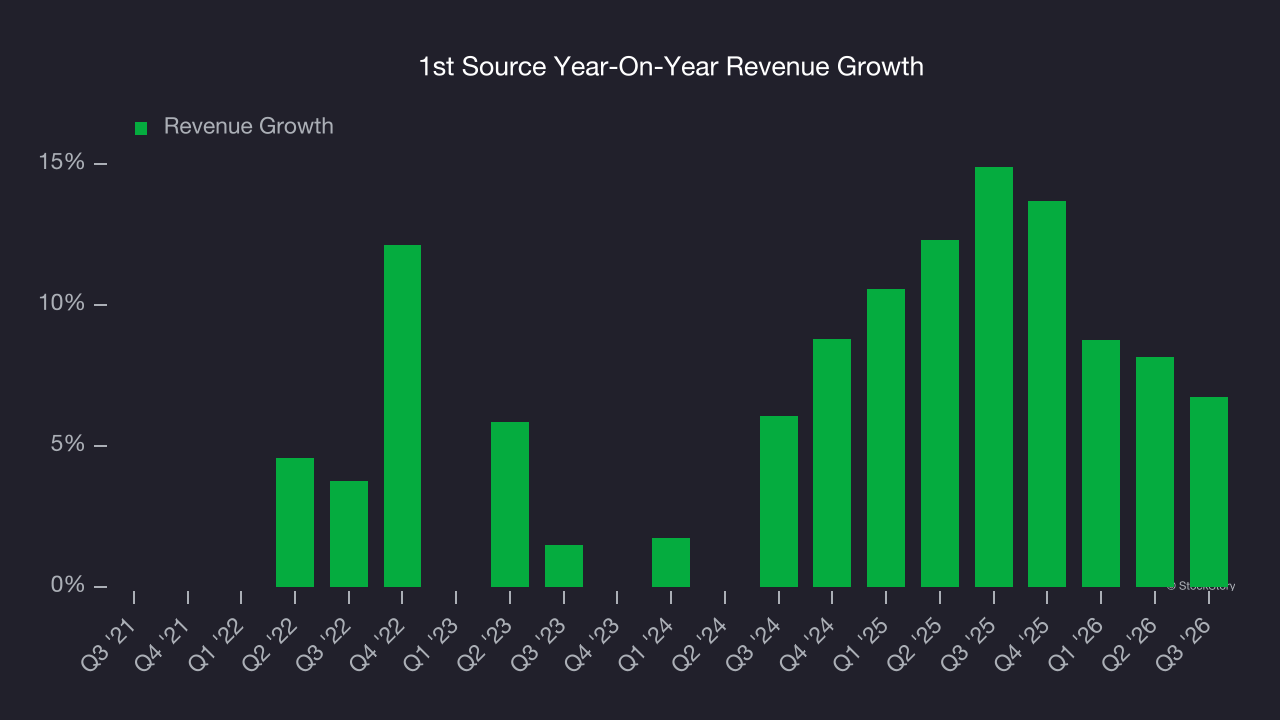 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, 1st Source reported year-on-year revenue growth of 6.7%, and its $120.3 million of revenue exceeded Wall Street’s estimates by 1.8%.
Net interest income made up 76.4% of the company’s total revenue during the last five years, meaning lending operations are 1st Source’s largest source of revenue.
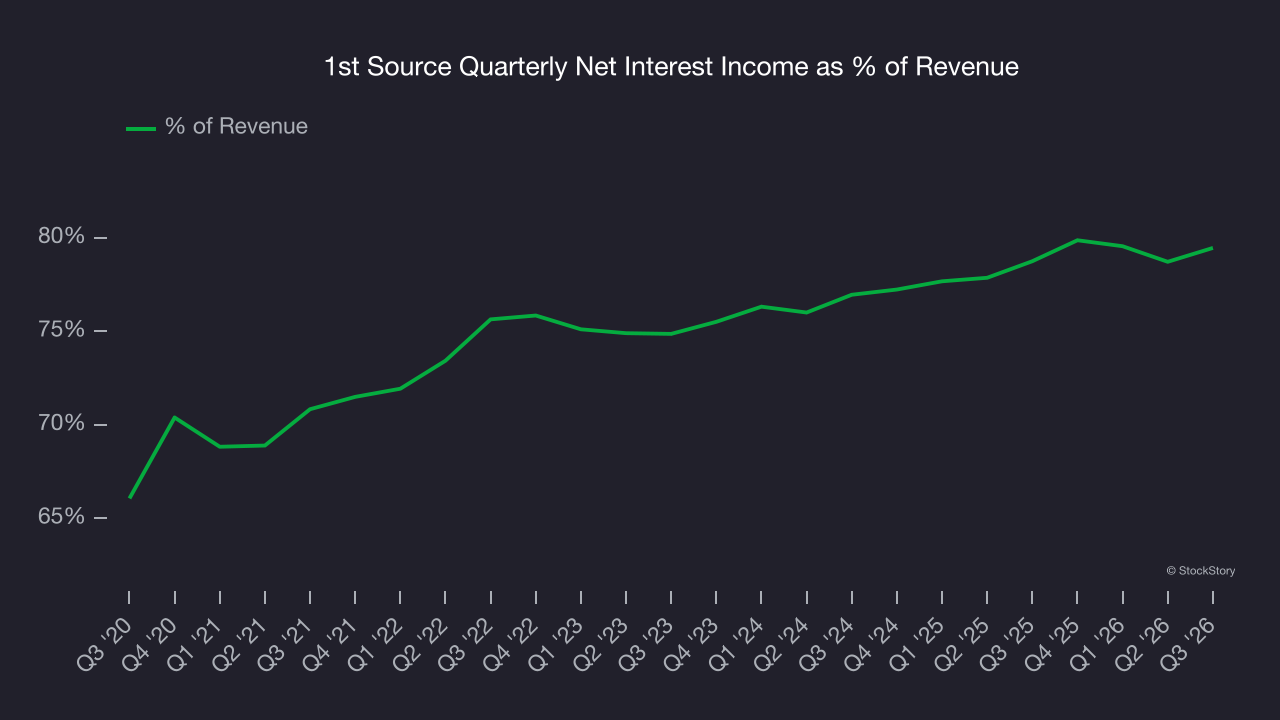
While banks generate revenue from multiple sources, investors view net interest income as the cornerstone - its predictable, recurring characteristics stand in sharp contrast to the volatility of non-interest income.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Tangible book value per share (TBVPS)
The balance sheet drives banking profitability since earnings flow from the spread between borrowing and lending rates. As such, valuations for these companies concentrate on capital strength and sustainable equity accumulation potential.
This is why we consider tangible book value per share (TBVPS) the most important metric to track for banks. TBVPS represents the real, liquid net worth per share of a bank, excluding intangible assets that have debatable value upon liquidation. Traditional metrics like EPS are helpful but face distortion from M&A activity and loan loss accounting rules.
1st Source’s TBVPS grew at an excellent 9% annual clip over the last five years. TBVPS growth has also accelerated recently, growing by 11% annually over the last two years from $41.62 to $51.31 per share.
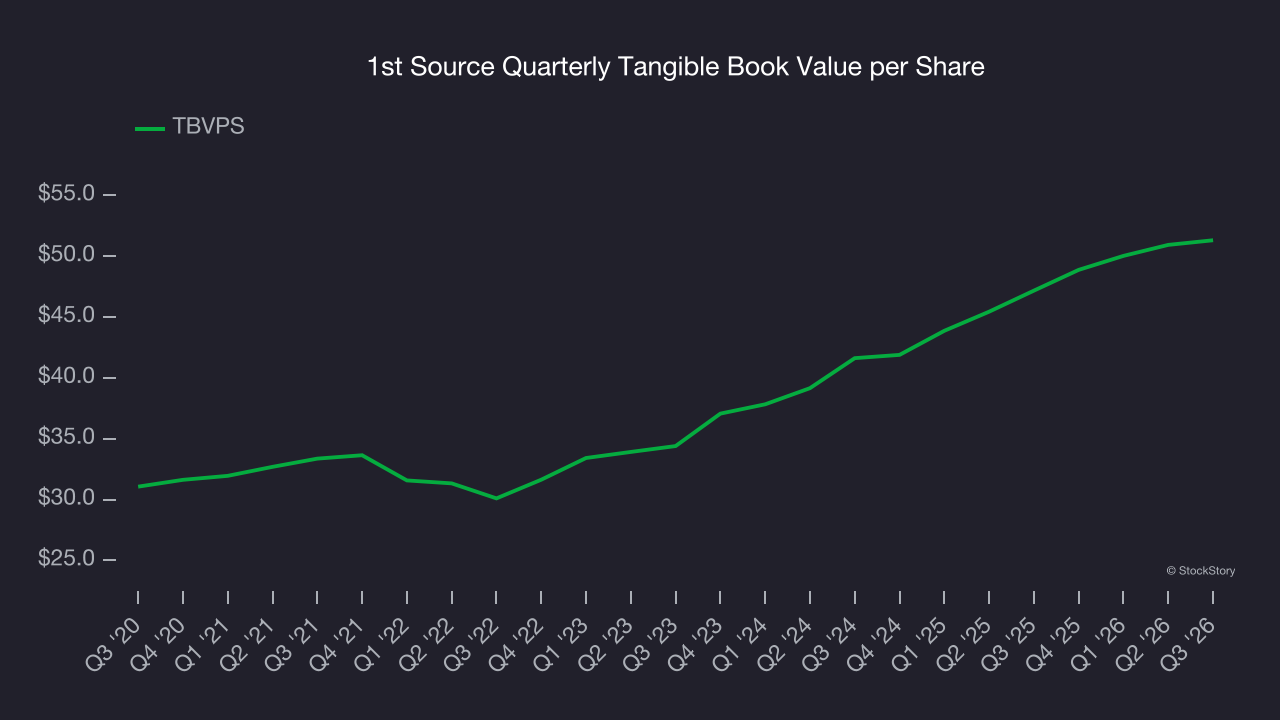
Over the next 12 months, Consensus estimates call for 1st Source’s TBVPS to grow by 11.9% to $57.41, mediocre growth rate.
Key takeaways from 1st Source’s Q3 results
It was good to see 1st Source beat analysts’ EPS expectations this quarter. We were also happy its revenue outperformed Wall Street’s estimates. On the other hand, its tangible book value per share slightly missed. Overall, this print had some key positives. The stock remained flat at $87.76 immediately following the results.
1st Source put up rock-solid earnings, but one quarter doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).




