
Regional banking company Eastern Bankshares (NASDAQ: EBC) missed Wall Street’s revenue expectations in Q3 2026, but sales rose 25.1% year on year to $306.6 million. Its non-GAAP profit of $0.51 per share was 3.8% above analysts’ consensus estimates.
Is now the time to buy Eastern Bank? Find out by accessing our full research report, it’s free.
Eastern Bank (EBC) Q3 2026 highlights:
- Net Interest Income: $257.9 million vs analyst estimates of $259.5 million (28.8% year-on-year growth, 0.6% miss)
- Net Interest Margin: 3.6% vs analyst estimates of 3.6% (in line)
- Revenue: $306.6 million vs analyst estimates of $311.6 million (25.1% year-on-year growth, 1.6% miss)
- Efficiency Ratio: 52.1% vs analyst estimates of 52.1% (in line)
- Adjusted EPS: $0.51 vs analyst estimates of $0.49 (3.8% beat)
- Tangible Book Value per Share: $12.96 vs analyst estimates of $13.25 (7.3% year-on-year decline, 2.2% miss)
- Market Capitalization: $4.71 billion
“We are pleased with our third quarter performance, which reflects disciplined execution on our priorities of growing organically and returning capital to shareholders,” said Denis Sheahan, Chief Executive Officer. “CRE and C&I lending drove solid total loan growth, while CRE payoffs continued to be a headwind, despite moderating from the second quarter. Commercial loan pipelines remain strong, although the pace of closings has been somewhat slower than anticipated as some clients take a more measured approach to investment decisions amid interest rate uncertainty. Overall, customers remain resilient and business activity continues to generate demand for financing. On the funding side, period-end deposits grew modestly despite seasonal municipal outflows. While competition remains elevated, we are committed to gathering core deposits to support our growth strategy. Wealth Management further increased assets under management and administration, and our comprehensive, team-based approach continues to differentiate us. While we are in the early stages of capitalizing on the full potential of our Wealth Management business, we are generating meaningful momentum, and are encouraged about its long-term outlook.”
Company overview
Founded in 1818 as one of America's oldest mutual banks before converting to a public company in 2020, Eastern Bankshares (NASDAQ: EBC) operates as a bank holding company providing commercial and retail banking services primarily in Massachusetts, New Hampshire, and Rhode Island.
Sales growth
Net interest income and fee-based revenue are the two pillars supporting bank earnings. The former captures profit from the gap between lending rates and deposit costs, while the latter encompasses charges for banking services, credit products, wealth management, and trading activities. Over the last five years, Eastern Bank grew its revenue at an impressive 15.2% compounded annual growth rate. Its growth beat the average banking company and shows its offerings resonate with customers.
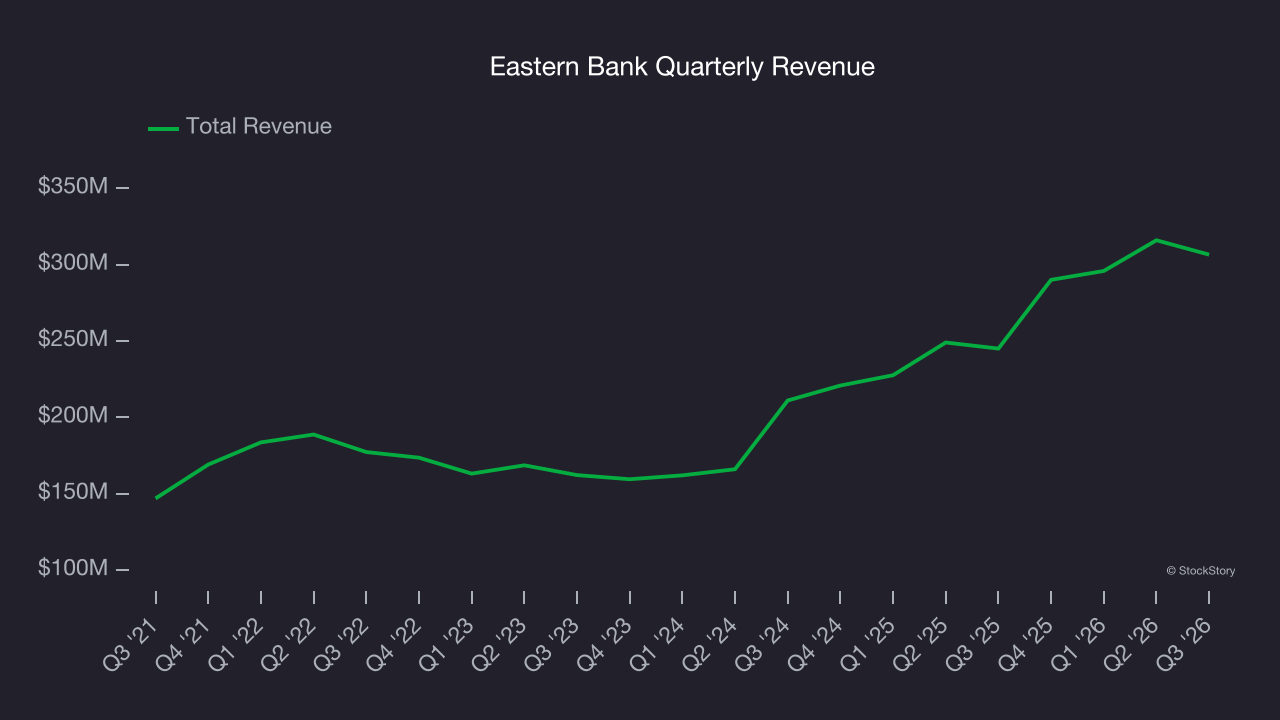
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Eastern Bank’s annualized revenue growth of 31.5% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 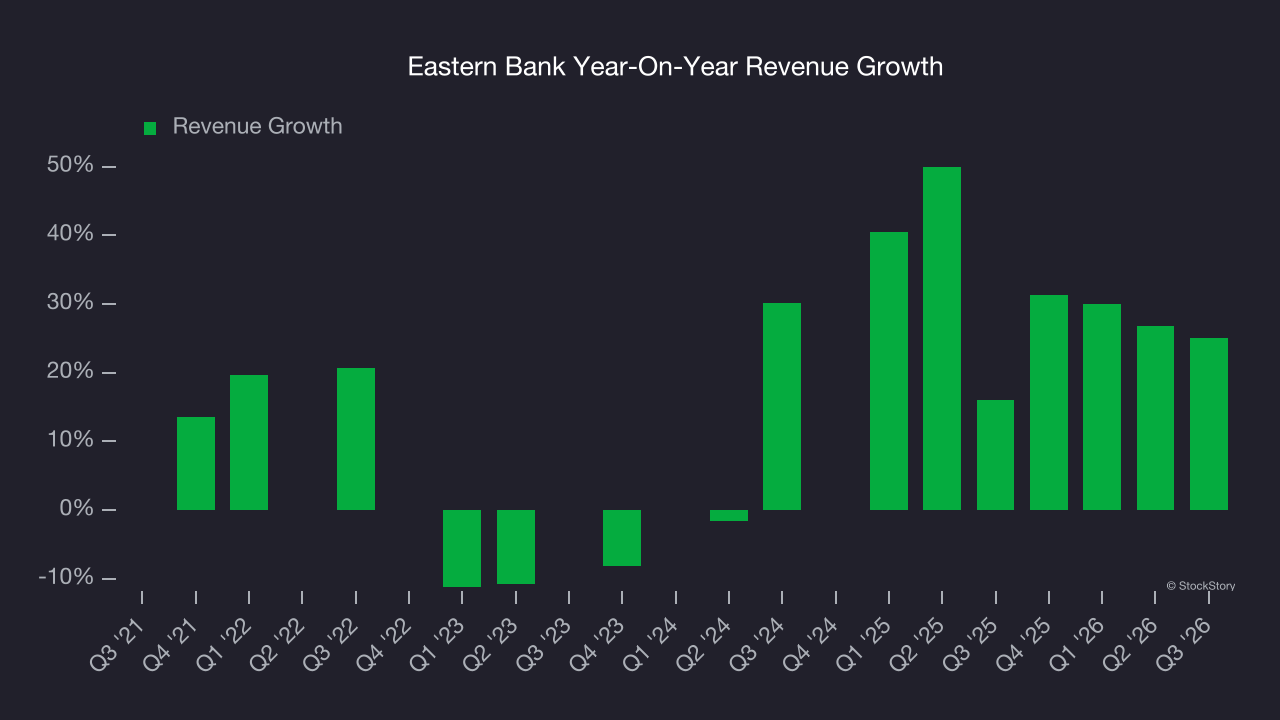 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Eastern Bank generated an excellent 25.1% year-on-year revenue growth rate, but its $306.6 million of revenue fell short of Wall Street’s high expectations.
Net interest income made up 81.3% of the company’s total revenue during the last five years, meaning Eastern Bank barely relies on non-interest income to drive its overall growth.
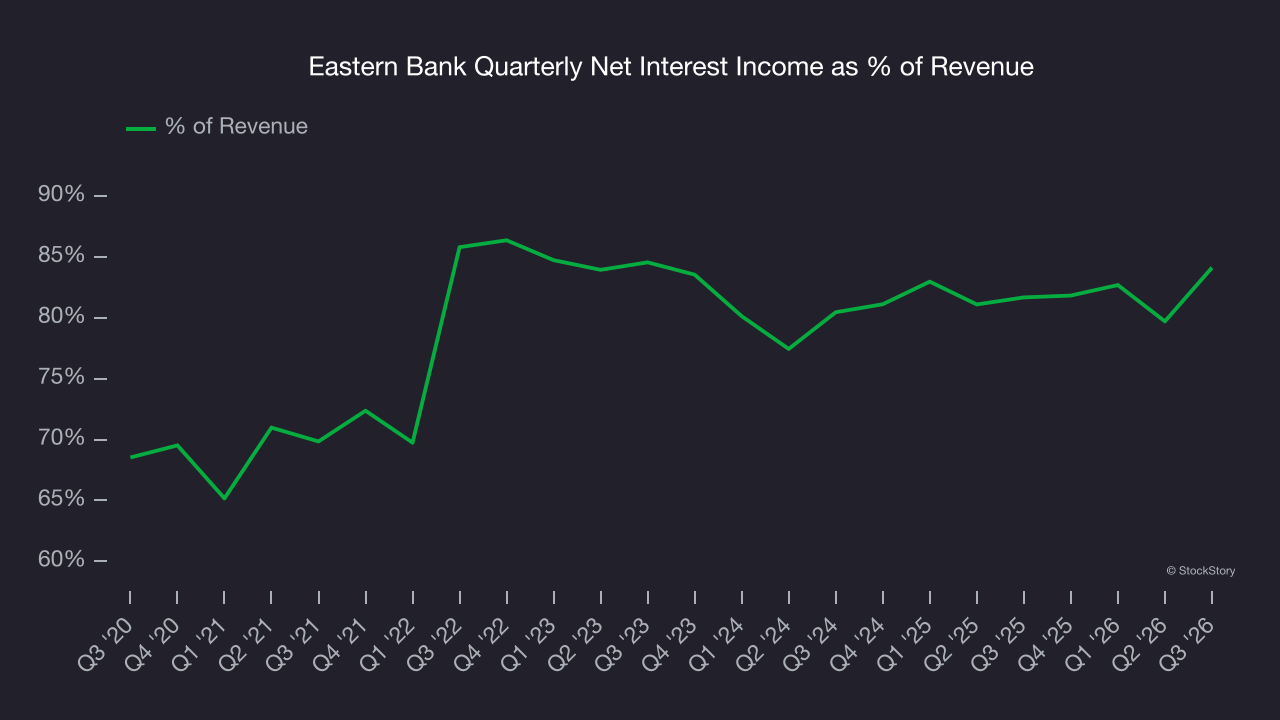
While banks generate revenue from multiple sources, investors view net interest income as the cornerstone - its predictable, recurring characteristics stand in sharp contrast to the volatility of non-interest income.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Tangible book value per share (TBVPS)
Banks are balance sheet-driven businesses because they generate earnings primarily through borrowing and lending. They’re also valued based on their balance sheet strength and ability to compound book value (another name for shareholders’ equity) over time.
Because of this, tangible book value per share (TBVPS) emerges as the critical performance benchmark. By excluding intangible assets with uncertain liquidation values, this metric captures real, liquid net worth per share. Traditional metrics like EPS are helpful but face distortion from M&A activity and loan loss accounting rules.
Eastern Bank’s TBVPS declined at a 6% annual clip over the last five years. On a two-year basis, TBVPS fell at a slower pace, dropping by 1.2% annually from $13.29 to $12.96 per share.
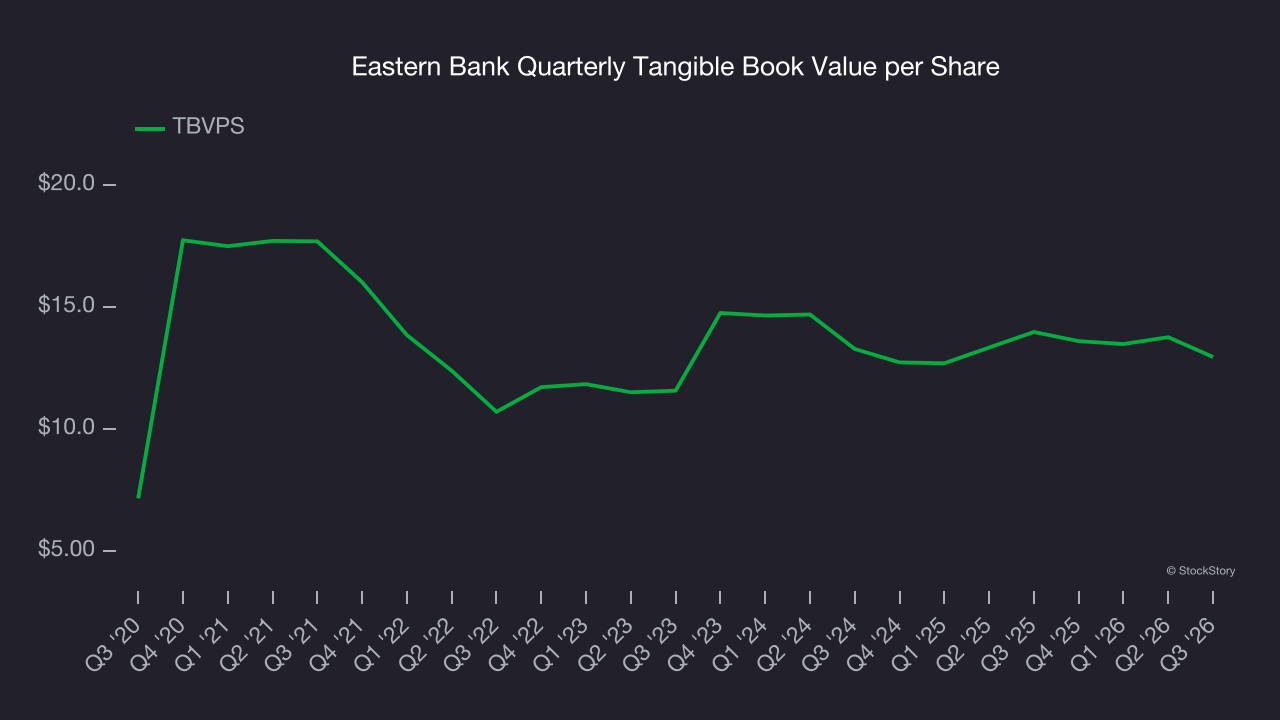
Over the next 12 months, Consensus estimates call for Eastern Bank’s TBVPS to grow by 11.9% to $14.50, mediocre growth rate.
Key takeaways from Eastern Bank’s Q3 results
We struggled to find many positives in these results. Its revenue missed and its tangible book value per share fell short of Wall Street’s estimates. Overall, this was a softer quarter. The stock remained flat at $22.12 immediately after reporting.
Is Eastern Bank an attractive investment opportunity right now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).




