
Electronic components manufacturer Knowles (NYSE: KN) reported Q3 2026 results beating Wall Street’s revenue expectations, with sales up 20.3% year on year to $184 million. On top of that, next quarter’s revenue guidance ($185 million at the midpoint) was surprisingly good and 6% above what analysts were expecting. Its non-GAAP profit of $0.38 per share was 6.3% above analysts’ consensus estimates.
Is now the time to buy Knowles? Find out by accessing our full research report, it’s free.
Knowles (KN) Q3 2026 highlights:
- Revenue: $184 million vs analyst estimates of $172.1 million (20.3% year-on-year growth, 6.9% beat)
- Adjusted EPS: $0.38 vs analyst estimates of $0.36 (6.3% beat)
- Adjusted EBITDA: $48.3 million vs analyst estimates of $45 million (26.3% margin, 7.3% beat)
- Revenue Guidance for Q4 2026 is $185 million at the midpoint, above analyst estimates of $174.6 million
- Adjusted EPS guidance for Q4 2026 is $0.41 at the midpoint, above analyst estimates of $0.38
- Operating Margin: 16.7%, in line with the same quarter last year
- Free Cash Flow Margin: 23.2%, up from 14% in the same quarter last year
- Market Capitalization: $2.98 billion
“Total Company revenue grew 20% year over year in the third quarter, and our book-to-bill ratio in Precision Devices remained above one for the eighth consecutive quarter, reflecting continued order strength,” Mr. Niew continued. “By executing our strategy—leveraging our differentiated technologies, developing custom products through close customer collaboration, and scaling production with our world-class operational capabilities—we delivered strong growth across the four major markets we serve: Medtech, Defense, Industrial, and Electrification. Additionally, at the mid-point of our fourth quarter guided range, full year 2026 revenue is expected to grow 16%. I am pleased with the Company’s performance and excited about the opportunities ahead.”
Company overview
With roots dating back to 1946 and a focus on components that must perform flawlessly in critical situations, Knowles (NYSE: KN) designs and manufactures specialized electronic components like high-performance capacitors, microphones, and speakers for medical technology, defense, and industrial applications.
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years.
With $666.1 million in revenue over the past 12 months, Knowles is a small player in the business services space, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and numerous distribution channels.
As you can see below, Knowles’s demand was weak over the last five years. Its sales fell by 5.4% annually, a tough starting point for our analysis.
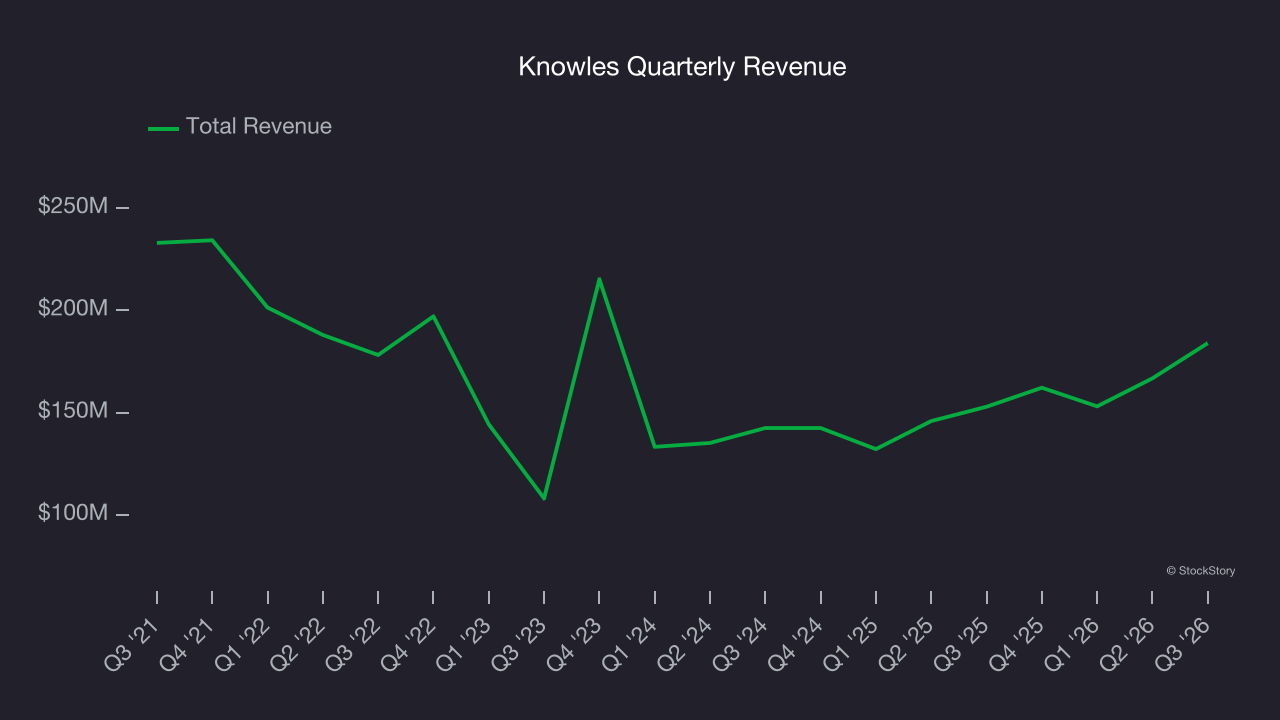
We at StockStory place the most emphasis on long-term growth, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Knowles’s annualized revenue growth of 3.1% over the last two years is above its five-year trend, which is encouraging. 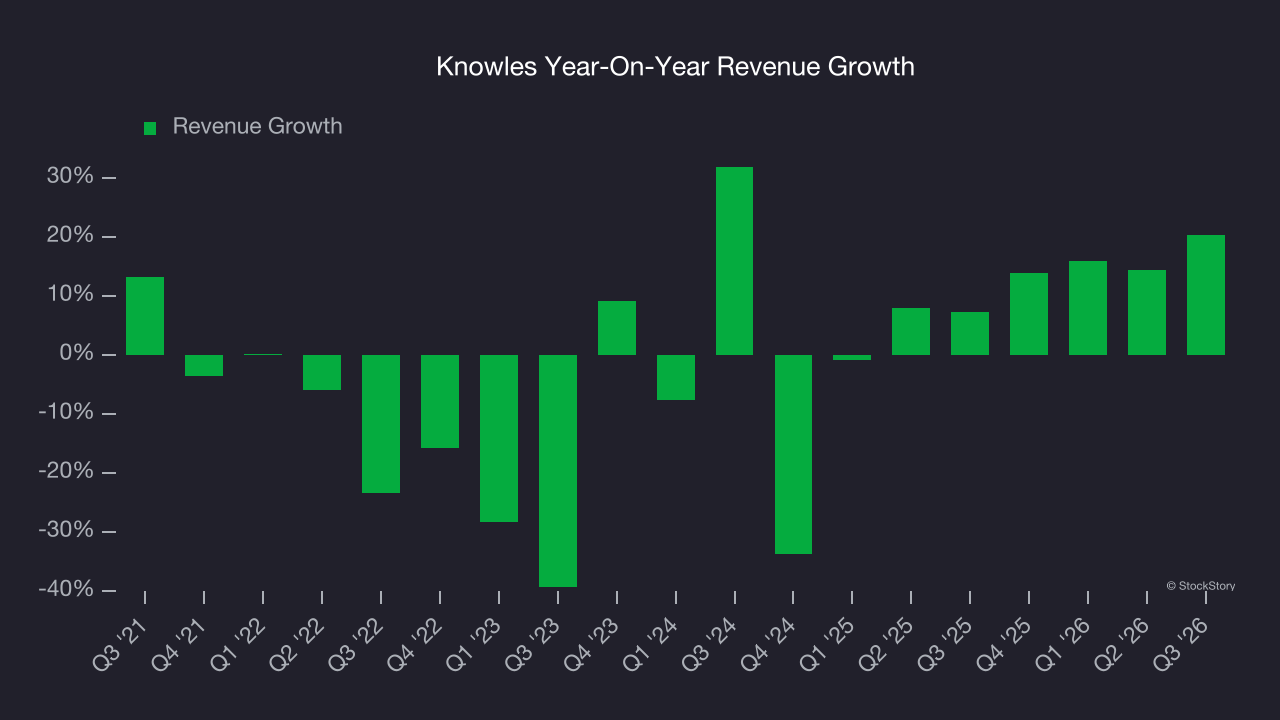
This quarter, Knowles reported robust year-on-year revenue growth of 20.3%, and its $184 million of revenue topped Wall Street estimates by 6.9%. Company management is currently guiding for a 14.1% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 5.9% over the next 12 months, an improvement versus the last two years. This projection is above average for the sector and suggests its newer products and services will fuel better top-line performance.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Adjusted operating margin
Knowles has been an efficient company over the last five years. It was one of the more profitable businesses in the business services sector, boasting an average adjusted operating margin of 16.1%.
Analyzing the trend in its profitability, Knowles’s adjusted operating margin rose by 2.2 percentage points over the last five years, showing its efficiency has improved.
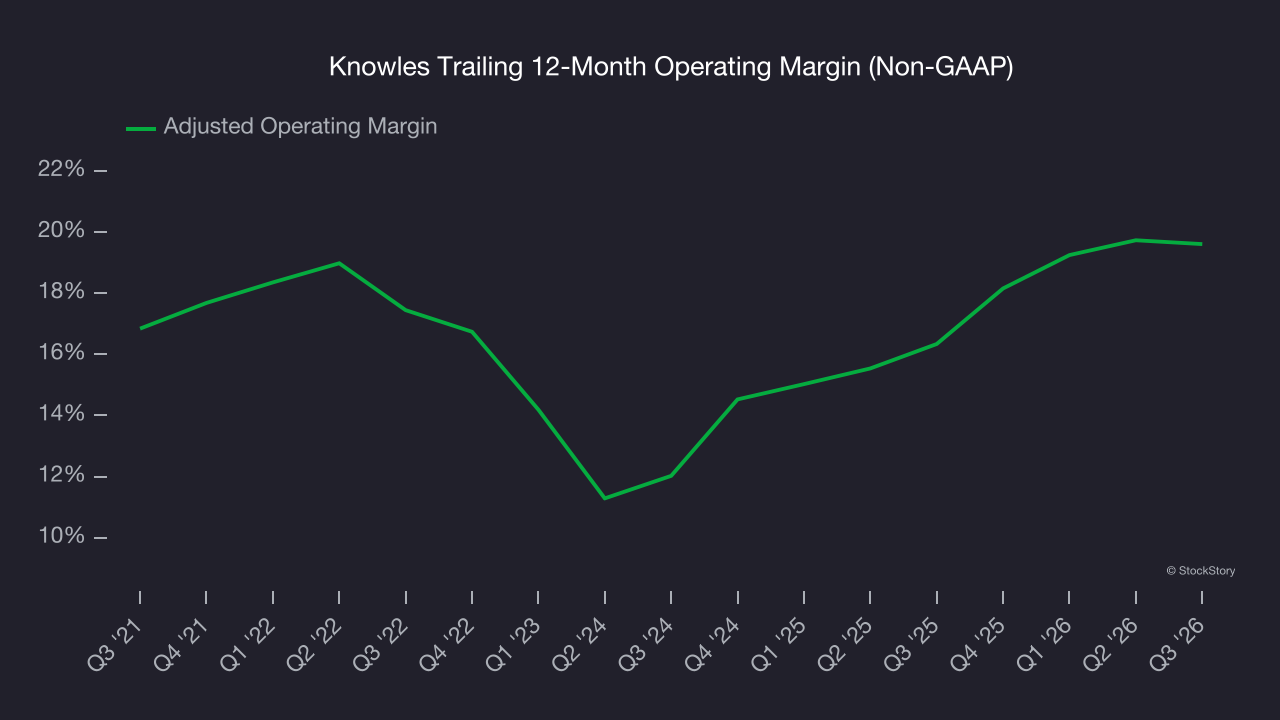
This quarter, Knowles generated an adjusted operating margin profit margin of 20.4%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Sadly for Knowles, its EPS and revenue declined by 1.7% and 5.4% annually over the last five years. We tend to steer our readers away from companies with falling revenue and EPS, where diminishing earnings could imply changing secular trends and preferences. If the tide turns unexpectedly, Knowles’s low margin of safety could leave its stock price susceptible to large downswings.
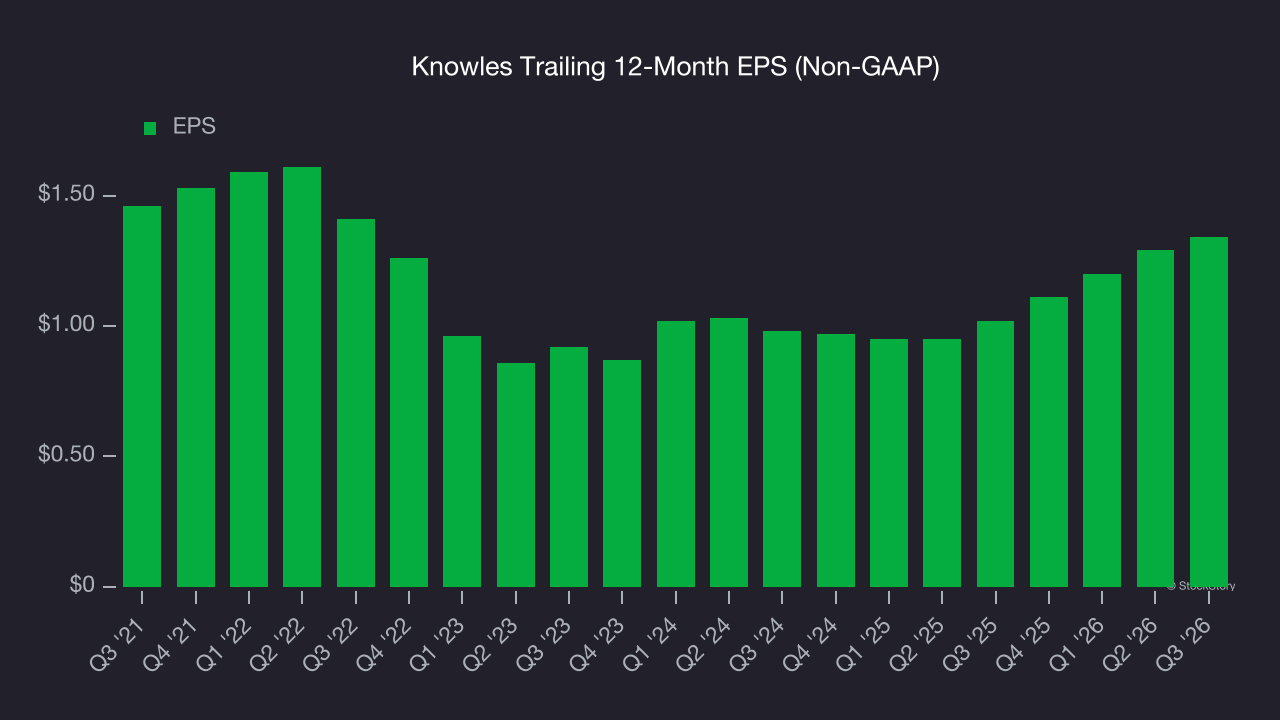
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Knowles, its two-year annual EPS growth of 16.9% was higher than its five-year trend. This acceleration made it one of the faster-growing business services companies in recent history.
In Q3, Knowles reported adjusted EPS of $0.38, up from $0.33 in the same quarter last year. This print beat analysts’ estimates by 6.3%. Over the next 12 months, Wall Street expects Knowles’s full-year EPS to grow 17.5% from $1.34 to $1.58.
Key takeaways from Knowles’s Q3 results
We were impressed by how significantly Knowles blew past analysts’ EPS guidance for next quarter expectations this quarter. We were also excited its revenue outperformed Wall Street’s estimates by a wide margin. Zooming out, we think this was a good print with some key areas of upside. The stock traded up 4.7% to $34.96 immediately after reporting.
Sure, Knowles had a solid quarter, but if we look at the bigger picture, is this stock a buy? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).




