
Global advertising giant Omnicom Group (NYSE: OMC) reported Q3 2026 results exceeding the market’s revenue expectations, with sales up 59.1% year on year to $6.42 billion. Its non-GAAP profit of $2.73 per share was 2.2% above analysts’ consensus estimates.
Is now the time to buy Omnicom Group? Find out by accessing our full research report, it’s free.
Omnicom Group (OMC) Q3 2026 highlights:
- Revenue: $6.42 billion vs analyst estimates of $6.16 billion (59.1% year-on-year growth, 4.3% beat)
- Adjusted EPS: $2.73 vs analyst estimates of $2.67 (2.2% beat)
- Operating Margin: 15.4%, up from 13.1% in the same quarter last year
- Organic Revenue rose 7.2% year on year
- Market Capitalization: $22.08 billion
"As we approach the one-year anniversary of the Interpublic acquisition, we continue to deliver the expected benefits of the combination. We've strengthened our competitive position and are on track to deliver $900 million in cost-reduction synergies in 2026 resulting in stronger organic revenue growth, operating margins, and earnings per share," said John Wren, Chairman and Chief Executive Officer of Omnicom. "With our integration nearly complete and our portfolio of companies and operations streamlined, we're focused on high-demand services and are well positioned to pursue future growth. We'll continue investing in our people and agentic technology to drive measurable business outcomes for our clients."
Company overview
With a vast network of creative agencies that helped craft some of the most memorable ad campaigns in history, Omnicom Group (NYSE: OMC) is a strategic holding company that provides advertising, marketing, and communications services to many of the world's largest companies.
Revenue growth
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years.
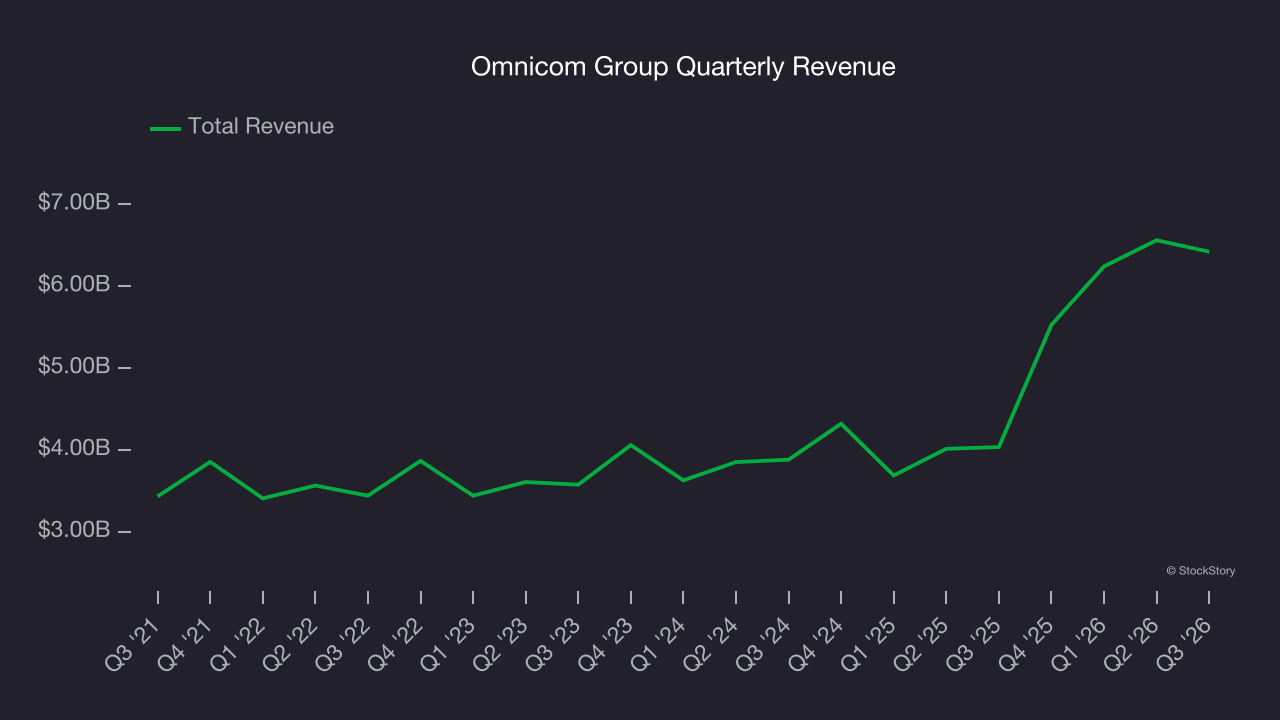
With $24.76 billion in revenue over the past 12 months, Omnicom Group is a behemoth in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices.
As you can see below, Omnicom Group’s sales grew at an excellent 11.8% compounded annual growth rate over the last five years. This is a great starting point for our analysis because it shows Omnicom Group’s demand was higher than many business services companies.
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. Omnicom Group’s annualized revenue growth of 26.7% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 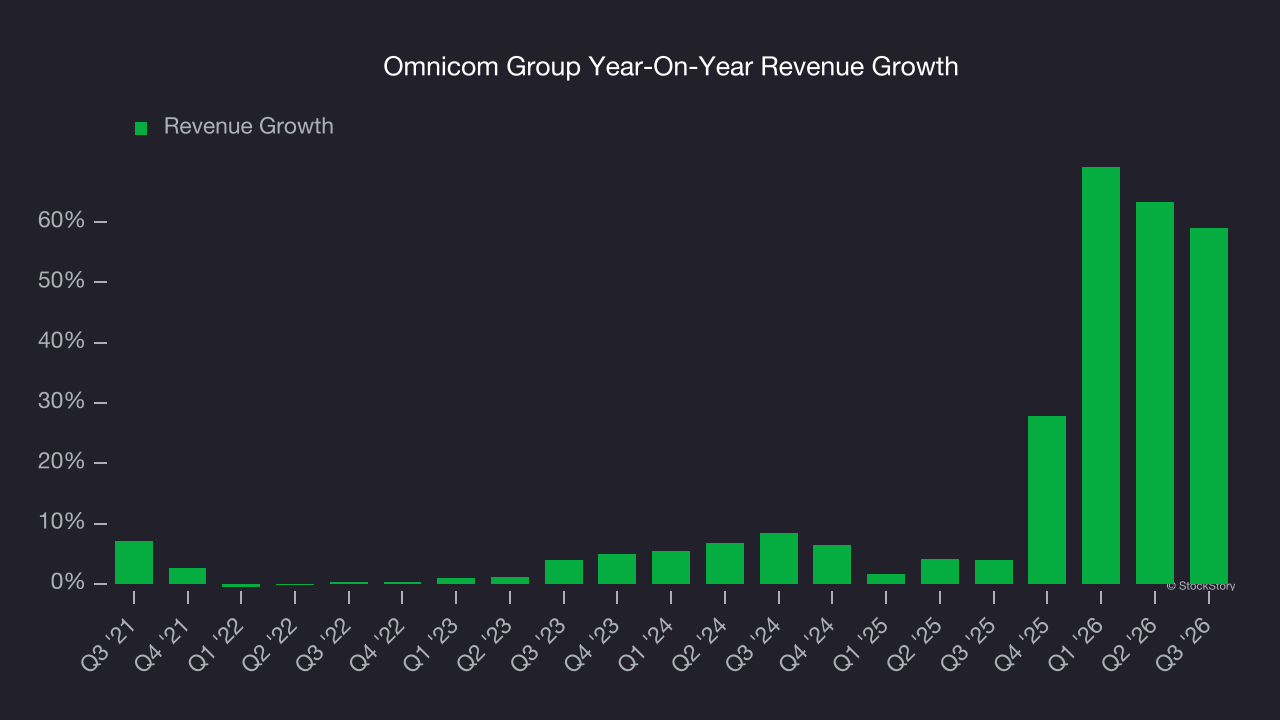
We can dig further into the company’s sales dynamics by analyzing its organic revenue, which strips out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Omnicom Group’s organic revenue averaged 4.5% year-on-year growth. Because this number is lower than its two-year revenue growth, we can see that some mixture of acquisitions and foreign exchange rates boosted its headline results. 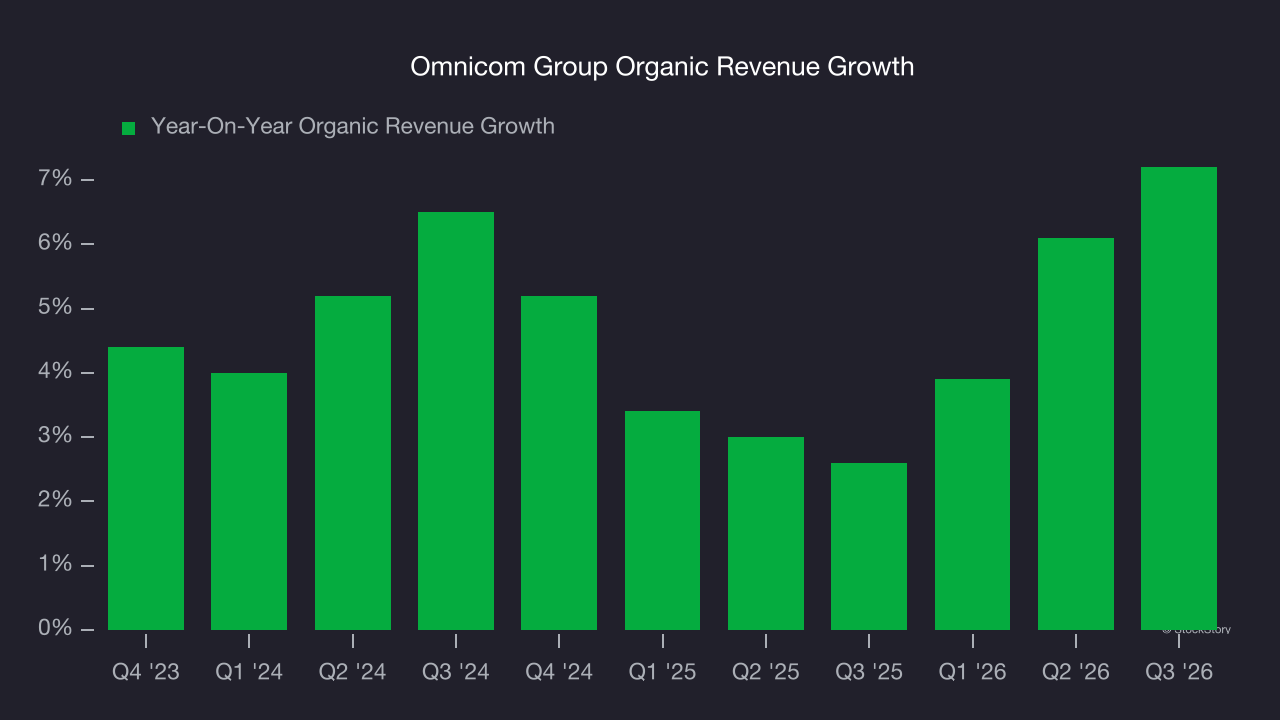
This quarter, Omnicom Group reported magnificent year-on-year revenue growth of 59.1%, and its $6.42 billion of revenue beat Wall Street’s estimates by 4.3%.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will see some demand headwinds. At least the company is tracking well in other measures of financial health.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Adjusted operating margin
Omnicom Group’s adjusted operating margin has more or less stayed the same over the last 12 months , averaging 15% over the last five years. This profitability was top-notch for a business services business, showing it’s a well-run company with an efficient cost structure.
Analyzing the trend in its profitability, Omnicom Group’s adjusted operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
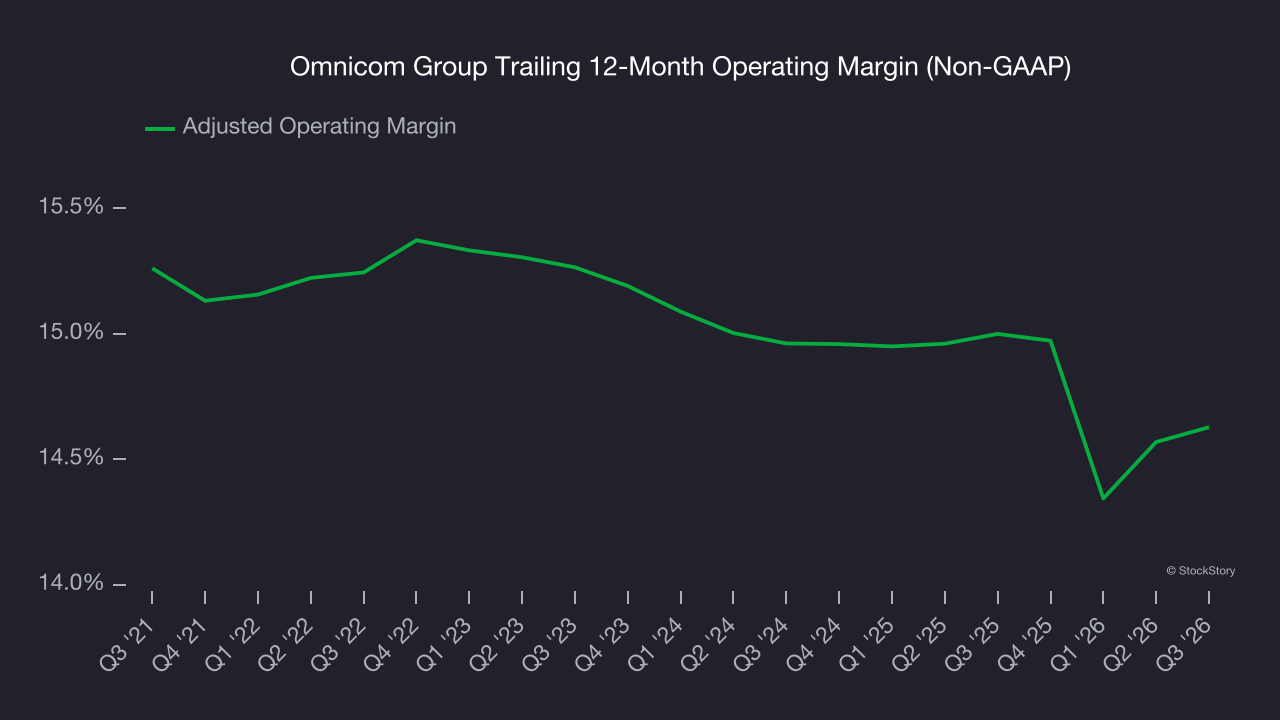
In Q3, Omnicom Group generated an adjusted operating margin profit margin of 15.4%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Omnicom Group’s EPS grew at a solid 9.7% compounded annual growth rate over the last five years. However, this performance was lower than its 11.8% annualized revenue growth, telling us the company became less profitable on a per-share basis as it expanded.
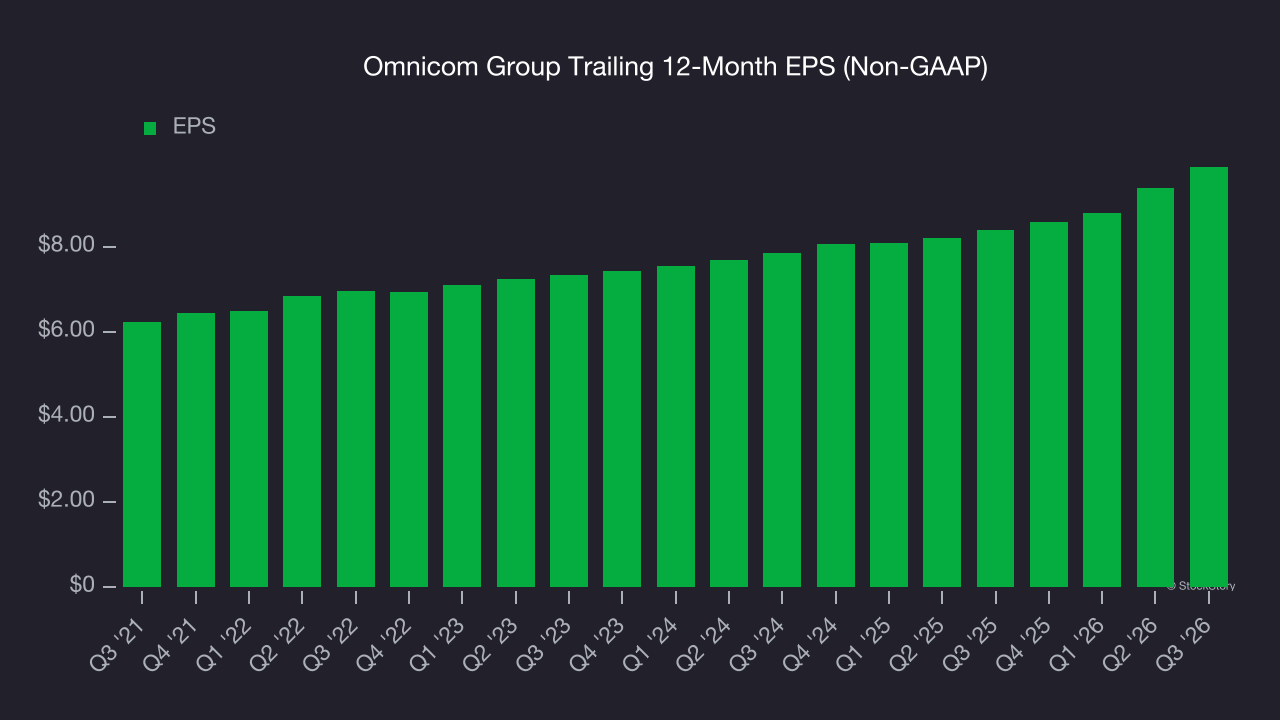
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Omnicom Group, its two-year annual EPS growth of 12.1% was higher than its five-year trend. We love it when earnings growth accelerates, especially when it accelerates off an already high base.
In Q3, Omnicom Group reported adjusted EPS of $2.73, up from $2.24 in the same quarter last year. This print beat analysts’ estimates by 2.2%. Over the next 12 months, Wall Street expects Omnicom Group’s full-year EPS to grow 11.2% from $9.87 to $10.97.
Key takeaways from Omnicom Group’s Q3 results
We enjoyed seeing Omnicom Group beat analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, we think this was a solid quarter with some key areas of upside. The stock traded up 1.1% to $83.50 immediately following the results.
Omnicom Group had an encouraging quarter, but one earnings result doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).




