
Cloud communications provider RingCentral (NYSE: RNG) reported Q3 2026 results exceeding the market’s revenue expectations, with sales up 5.9% year on year to $676 million. Guidance for next quarter’s revenue was better than expected at $676.5 million at the midpoint, 0.6% above analysts’ estimates. Its non-GAAP profit of $1.33 per share was 4.3% above analysts’ consensus estimates.
Is now the time to buy RingCentral? Find out by accessing our full research report, it’s free.
RingCentral (RNG) Q3 2026 highlights:
- Revenue: $676 million vs analyst estimates of $667.4 million (5.9% year-on-year growth, 1.3% beat)
- Adjusted EPS: $1.33 vs analyst estimates of $1.27 (4.3% beat)
- Adjusted EBITDA: $190.3 million vs analyst estimates of $183.5 million (28.1% margin, 3.7% beat)
- Revenue Guidance for Q4 2026 is $676.5 million at the midpoint, roughly in line with what analysts were expecting
- Management raised its full-year Adjusted EPS guidance to $5.10 at the midpoint, a 1.3% increase
- Operating Margin: 8%, up from 4.8% in the same quarter last year
- Free Cash Flow Margin: 23.2%, down from 27.4% in the previous quarter
- Billings: $676.8 million at quarter end, up 6.1% year on year
- Market Capitalization: $6.88 billion
“Voice is central to the next wave of AI innovation, and RingCentral is uniquely positioned to lead this transformation,” said Vlad Shmunis, Founder, Chairman and CEO of RingCentral. “Our trusted communications platform and expanding Agentic Voice AI portfolio puts us at the front door of customer interactions. By bringing communications, contact center, and AI together, we are redefining how businesses engage with customers, turning conversations into intelligent actions, better experiences, and measurable business outcomes. We see a significant opportunity ahead as businesses embrace the next generation of AI-powered customer engagement.”
Company overview
Built on its proprietary Message Video Phone (MVP) platform that unifies multiple communication methods, RingCentral (NYSE: RNG) provides AI-driven cloud communications and collaboration solutions that enable businesses to connect through voice, video, messaging, and contact center services.
Revenue growth
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, RingCentral grew its sales at a 12.1% annual rate. Though this growth is acceptable on an absolute basis, we need to see more than just topline growth for the software sector, which can display significant earnings volatility. This means our bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, five-year CAGR starts around Covid, when revenue was depressed then rebounded.
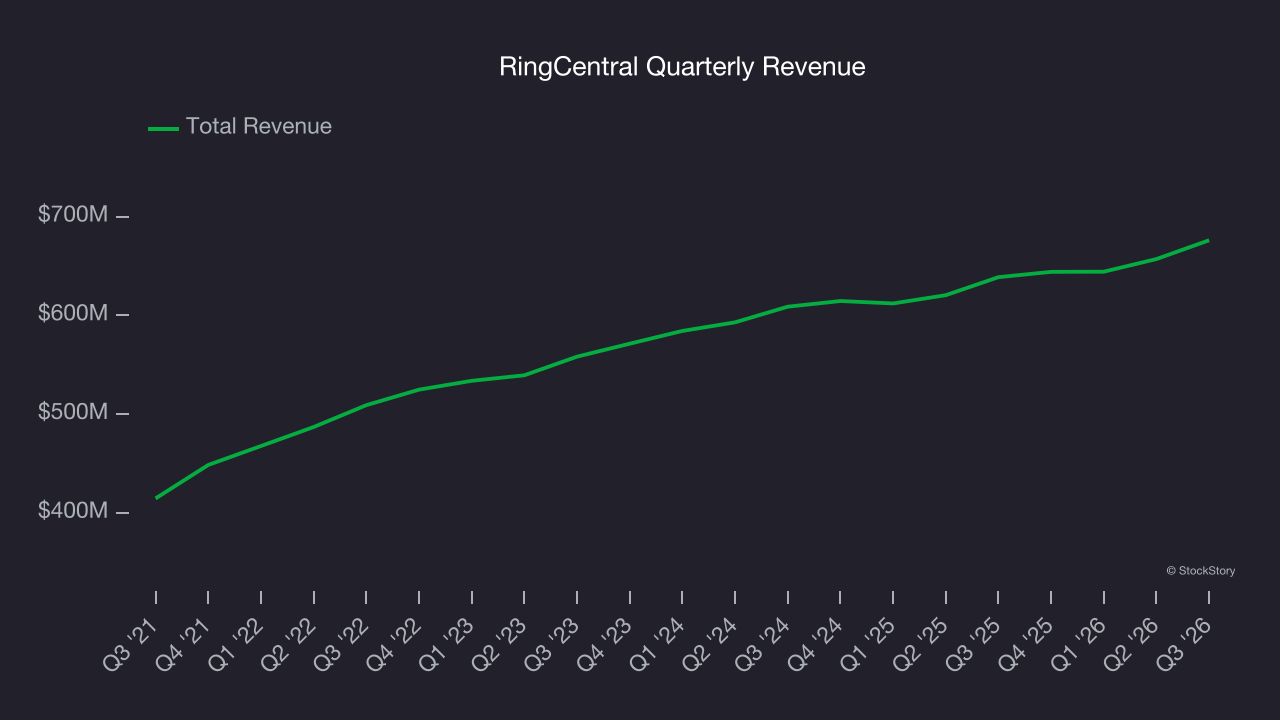
Long-term growth is the most important, but within software, a half-decade historical view may miss new innovations or demand cycles. RingCentral’s recent performance shows its demand has slowed as its annualized revenue growth of 5.5% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 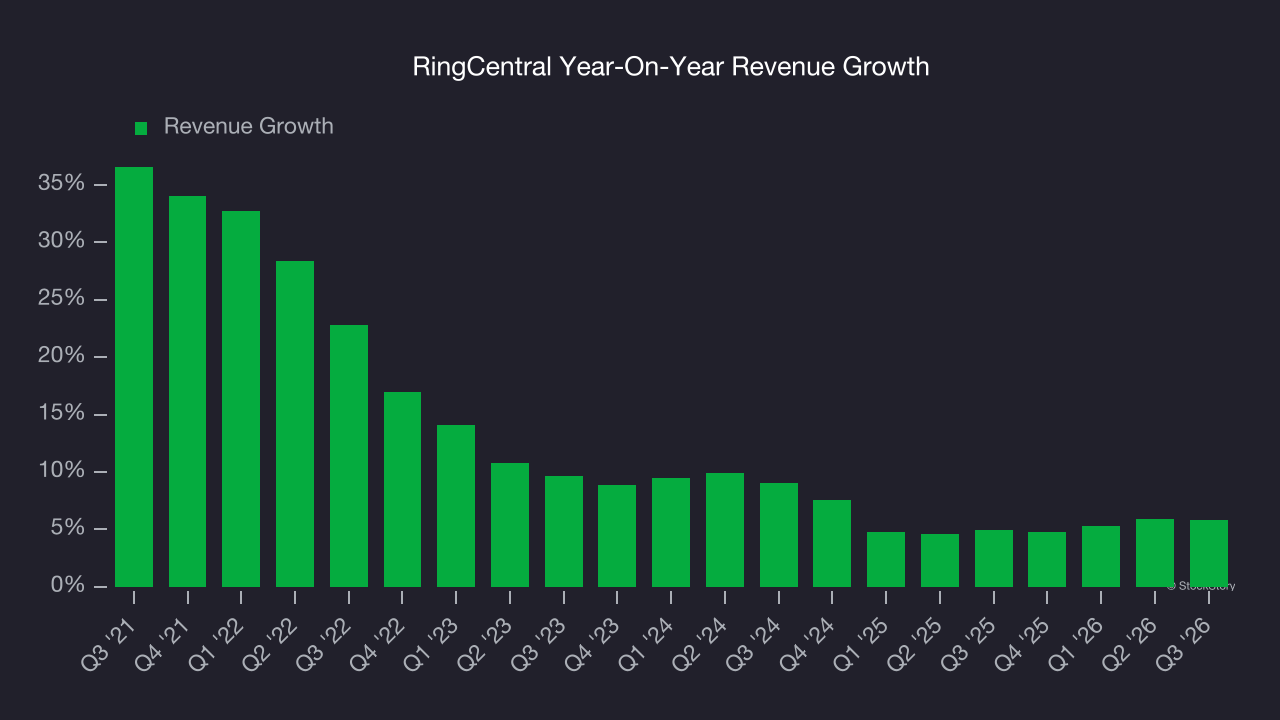
This quarter, RingCentral reported year-on-year revenue growth of 5.9%, and its $676 million of revenue exceeded Wall Street’s estimates by 1.3%. Company management is currently guiding for a 5% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 4.1% over the next 12 months, similar to its two-year rate. This projection doesn’t excite us and implies its products and services will face some demand challenges.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Billings
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
RingCentral’s billings came in at $676.8 million in Q3, and over the last four quarters, its growth was underwhelming as it averaged 6.8% year-on-year increases. This performance mirrored its total sales and suggests that increasing competition is causing challenges in acquiring/retaining customers. 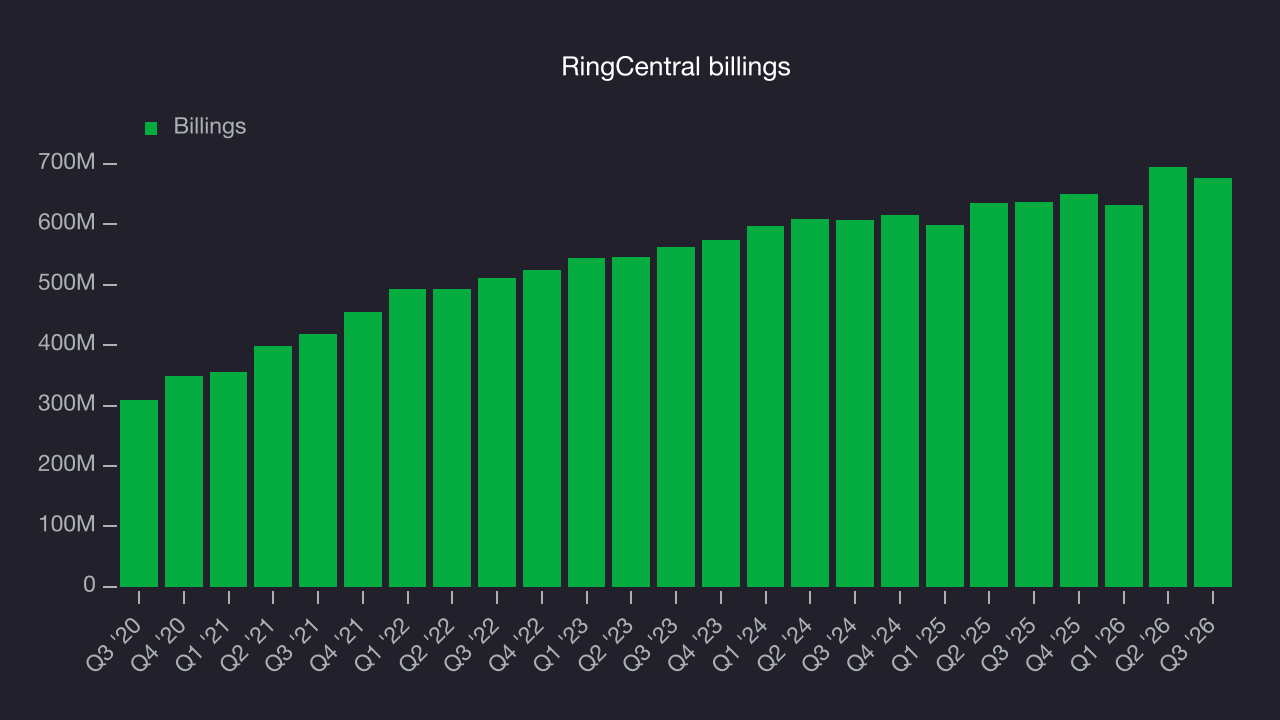
Customer acquisition efficiency
The customer acquisition cost (CAC) payback period represents the months required to recover the cost of acquiring a new customer. Essentially, it’s the break-even point for sales and marketing investments. A shorter CAC payback period is ideal, as it implies better returns on investment and business scalability.
It’s relatively expensive for RingCentral to acquire new customers as its CAC payback period checked in at 1,808.7 months this quarter. The company’s slow recovery of its sales and marketing expenses indicates it operates in a highly competitive market and must invest to stand out, even if the return on that investment is low.
Key takeaways from RingCentral’s Q3 results
We enjoyed seeing RingCentral beat analysts’ adjusted operating income expectations this quarter. We were also happy its billings outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock traded up 14.8% to $91.14 immediately following the results.
RingCentral put up rock-solid earnings, but one quarter doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).




