
Financial software provider SS&C Technologies (NASDAQ: SSNC) met Wall Street’s revenue expectations in Q3 2026, with sales up 7.7% year on year to $1.69 billion. On the other hand, next quarter’s revenue guidance of $1.72 billion was less impressive, coming in 1.5% below analysts’ estimates. Its non-GAAP profit of $1.78 per share was 0.7% above analysts’ consensus estimates.
Is now the time to buy SS&C? Find out by accessing our full research report, it’s free.
SS&C (SSNC) Q3 2026 highlights:
- Revenue: $1.69 billion vs analyst estimates of $1.69 billion (7.7% year-on-year growth, in line)
- Adjusted EPS: $1.78 vs analyst estimates of $1.77 (0.7% beat)
- Adjusted EBITDA: $674.8 million vs analyst estimates of $668.8 million (39.9% margin, 0.9% beat)
- Revenue Guidance for Q4 2026 is $1.72 billion at the midpoint, below analyst estimates of $1.75 billion
- Management slightly raised its full-year Adjusted EPS guidance to $7.14 at the midpoint
- Operating Margin: 24.2%, in line with the same quarter last year
- Free Cash Flow Margin: 28.5%, up from 23.3% in the same quarter last year
- Market Capitalization: $20.44 billion
"SS&C delivered another quarter of strong results, with Q3 organic revenue growth of 5.2%, record adjusted consolidated EBITDA of $674.8 million, and margins of 39.9%, keeping us on track to achieve our full-year goals," said Bill Stone, Chairman and Chief Executive Officer. "In September, we hosted over 1,000 financial services and healthcare leaders at our annual SS&C Deliver conference, and it was clear that holistic transformation of our clients’ operating models is a top priority. As we harness emerging technologies like agentic AI and tokenization, SS&C is evolving in step with our clients—partnering with them, supporting them, and shaping the future together."
Company overview
Founded in 1986 as a bridge between technology and financial services, SS&C Technologies (NASDAQ: SSNC) provides software and software-enabled services that help financial firms and healthcare organizations automate complex business processes.
Revenue growth
A company’s long-term sales performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
With $6.69 billion in revenue over the past 12 months, SS&C is one of the larger companies in the business services industry and benefits from a well-known brand that influences purchasing decisions.
As you can see below, SS&C’s 6.1% annualized revenue growth over the last five years was decent. This shows its offerings generated slightly more demand than the average business services company, a useful starting point for our analysis.
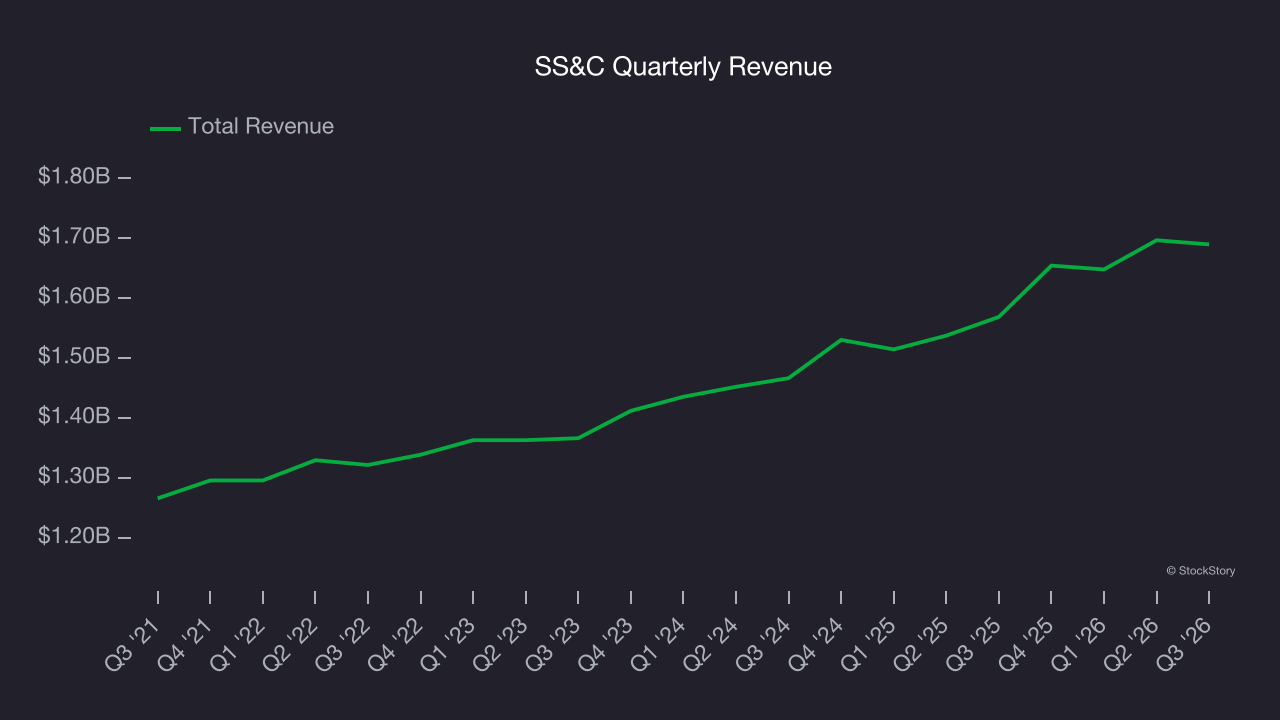
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. SS&C’s annualized revenue growth of 7.7% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 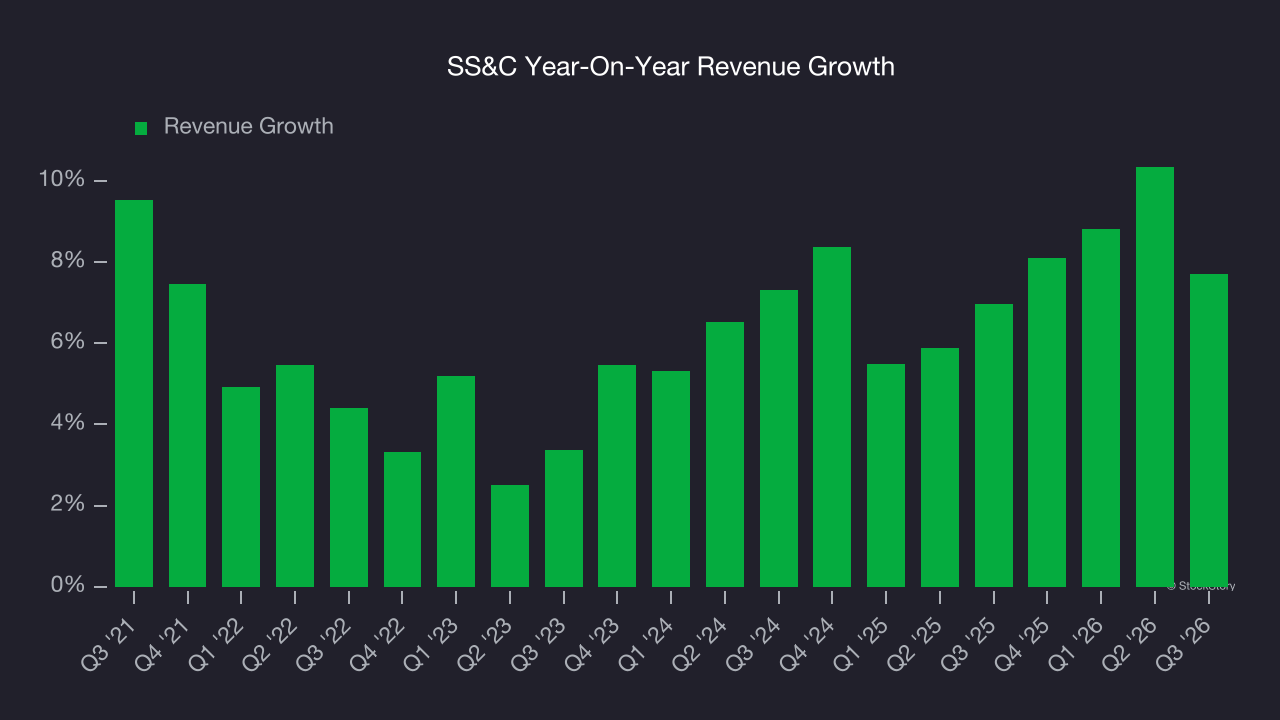
This quarter, SS&C grew its revenue by 7.7% year on year, and its $1.69 billion of revenue was in line with Wall Street’s estimates. Company management is currently guiding for a 4% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 5.1% over the next 12 months, a slight deceleration versus the last two years. Still, this projection is above average for the sector and indicates the market sees some success for its newer products and services.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Adjusted operating margin
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt, and taxes.
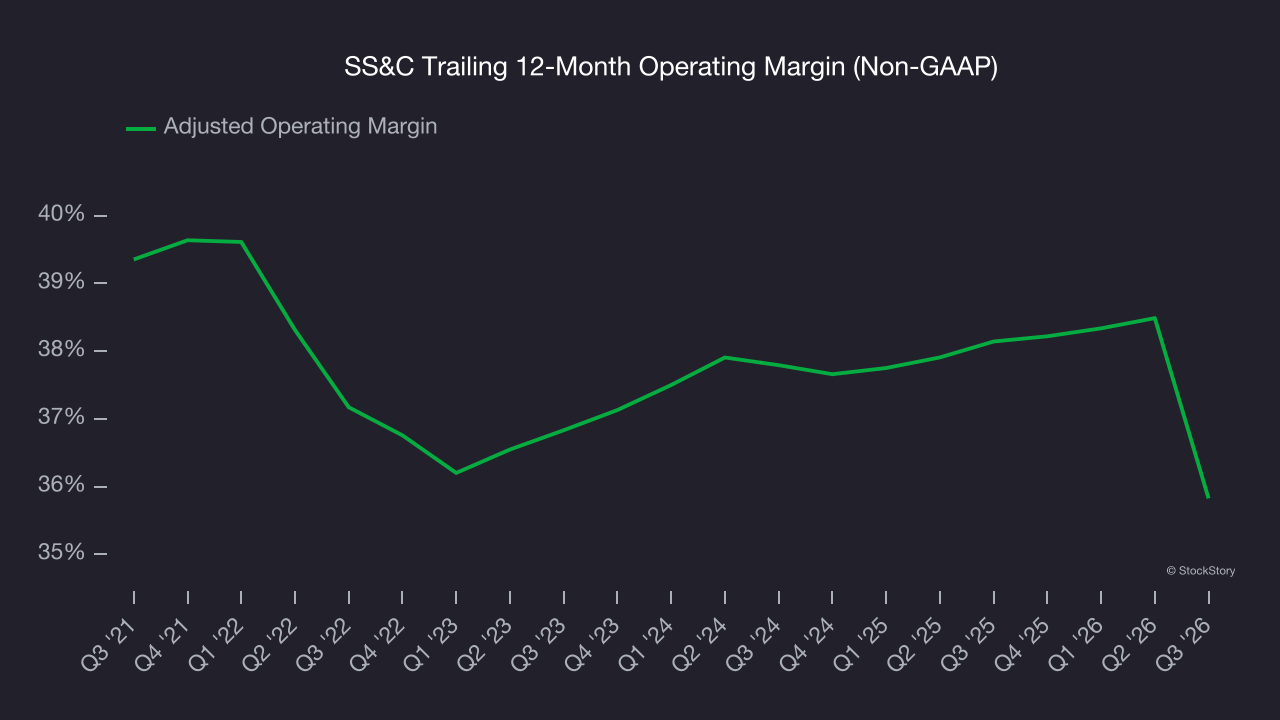
SS&C has been a well-oiled machine over the last five years. It demonstrated elite profitability for a business services business, boasting an average adjusted operating margin of 37.1%.
Looking at the trend in its profitability, SS&C’s adjusted operating margin decreased by 1.3 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
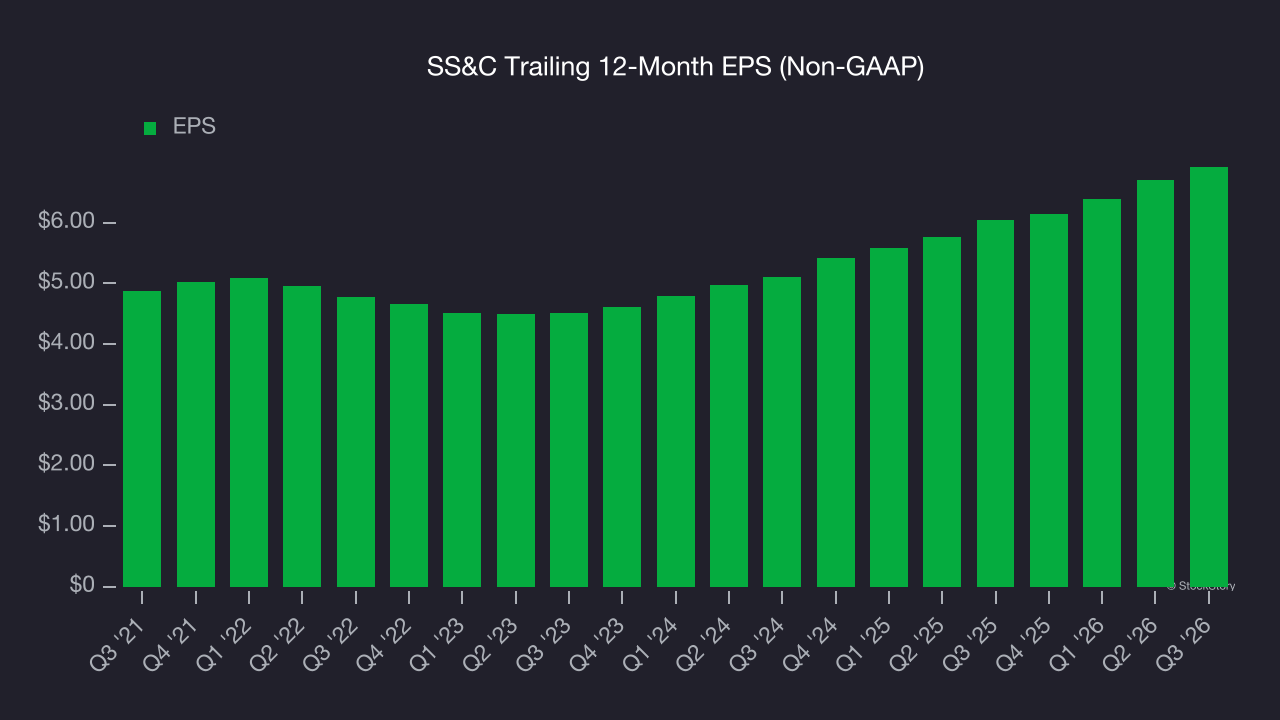
SS&C’s unimpressive 7.3% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
SS&C’s two-year annual EPS growth of 16.5% was great and topped its 7.7% two-year revenue growth.
Diving into SS&C’s quality of earnings can give us a better understanding of its performance. A two-year view shows that SS&C has repurchased its stock, shrinking its share count by 5.3%. This tells us its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings. 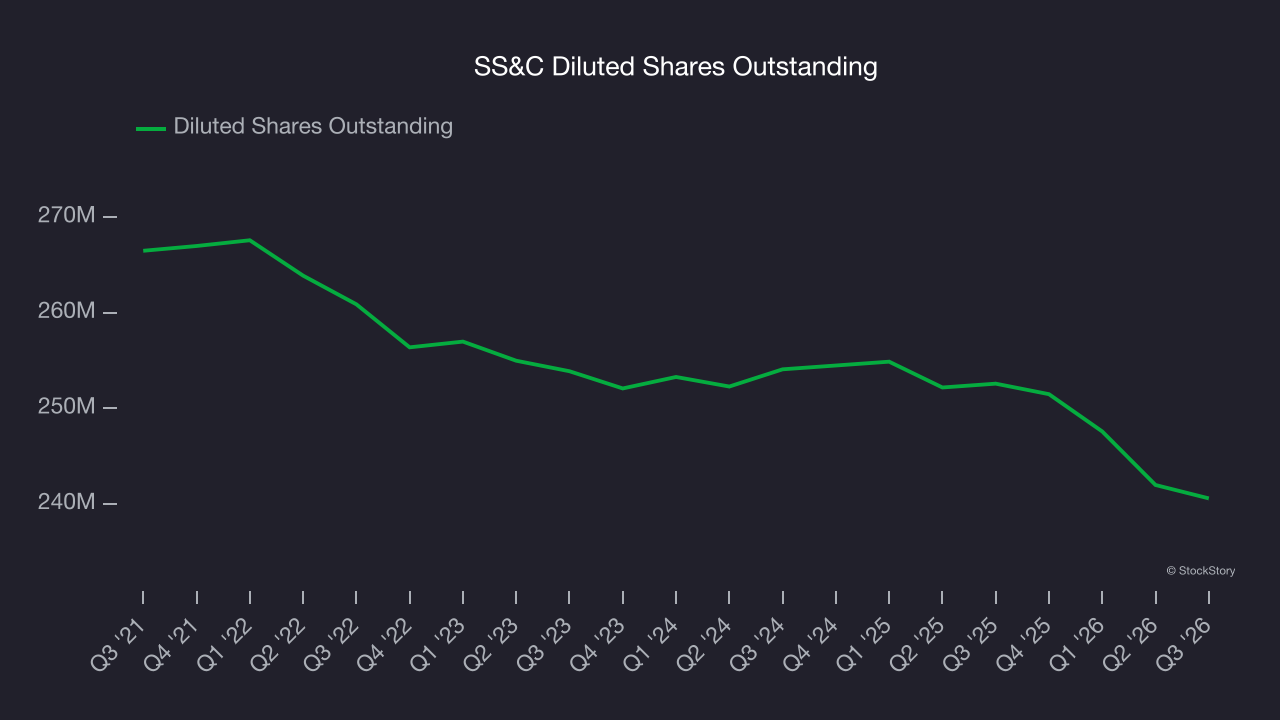
In Q3, SS&C reported adjusted EPS of $1.78, up from $1.57 in the same quarter last year. This print was close to analysts’ estimates. Over the next 12 months, Wall Street expects SS&C’s full-year EPS to grow 9.9% from $6.92 to $7.60.
Key takeaways from SS&C’s Q3 results
It was good to see SS&C narrowly top analysts’ full-year EPS guidance expectations this quarter. We were also happy its EPS guidance for next quarter narrowly outperformed Wall Street’s estimates. On the other hand, its revenue guidance for next quarter missed. Overall, this quarter could have been better. The stock traded down 6% to $84.11 immediately after reporting.
So should you invest in SS&C right now? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).




