Oilfield services company RPC (NYSE: RES) will be announcing earnings results this Thursday before market open. Here’s what to expect.
RPC beat analysts’ revenue expectations last quarter, reporting revenues of $460.9 million, up 9.5% year on year. It was a stunning quarter for the company, with a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
Is RPC a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting RPC’s revenue to grow 4.4% year on year, slowing from the 32.4% increase it recorded in the same quarter last year.
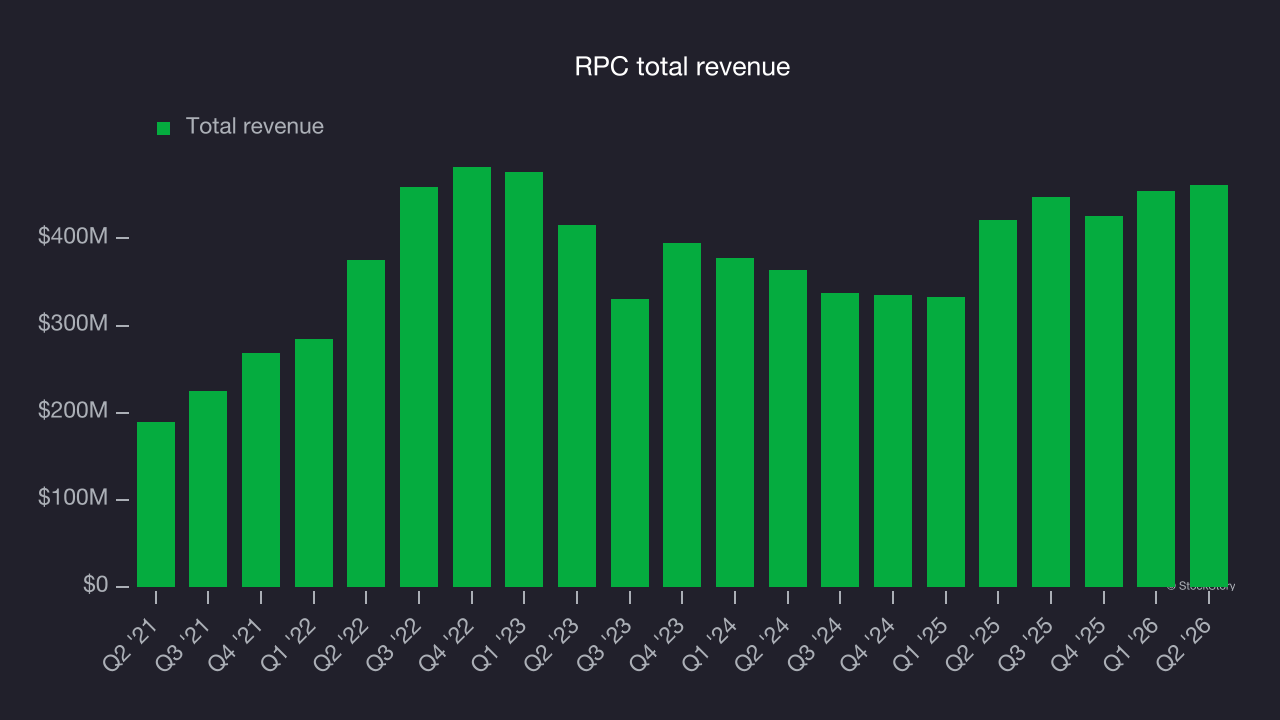
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. RPC rarely misses Wall Street’s revenue estimates.
Looking at RPC’s peers in the oilfield services segment, some have already reported their Q3 results, giving us a hint as to what we can expect. Baker Hughes delivered year-on-year revenue growth of 14.5%, beating analysts’ expectations by 3%, and NOV reported revenues up 2.3%, topping estimates by 1.5%.
Read our full analysis of Baker Hughes’s results here and NOV’s results here.
There has been positive sentiment among investors in the oilfield services segment, with share prices up 5.9% on average over the last month. RPC is up 14.5% during the same time and is heading into earnings with an average analyst price target of $6.40 (compared to the current share price of $6.56).
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.