Domino's has been treading water for the past six months, recording a small return of 2.4% while holding steady at $339.86.
Is there a buying opportunity in Domino's, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why is Domino's not exciting?
We’re passing on Domino's for now. Here are three reasons we avoid DPZ, plus one stock we’d rather own.
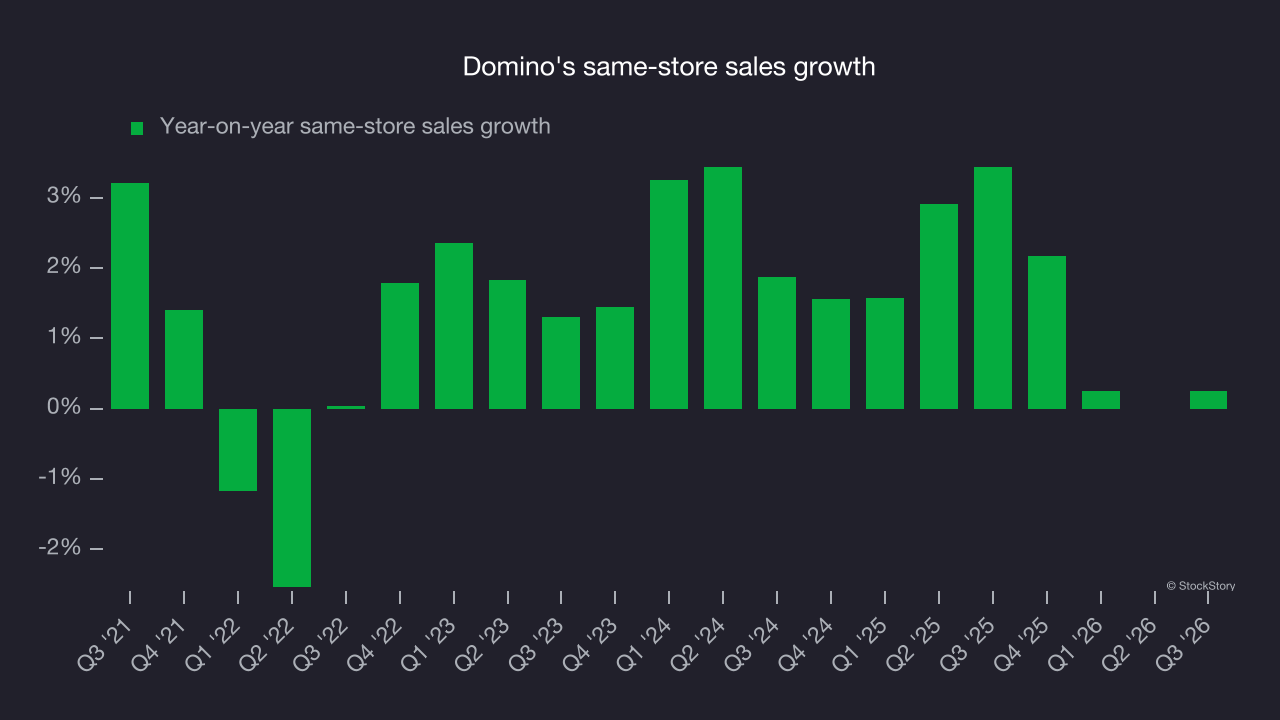
1. Same-store sales falling behind peers
Same-store sales show the change in sales at restaurants open for at least a year. This is a key performance indicator because it measures organic growth.
Domino’s demand within its existing dining locations has been relatively stable over the last two years but was below most restaurant chains. On average, the company’s same-store sales have grown by 1.5% per year.
2. Projected revenue growth is slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Domino’s revenue to rise by 4.8%, according to S&P, close to its 5.2% annualized growth for the past seven years. This projection doesn’t excite us and indicates its newer menu offerings will not lead to better top-line performance yet.
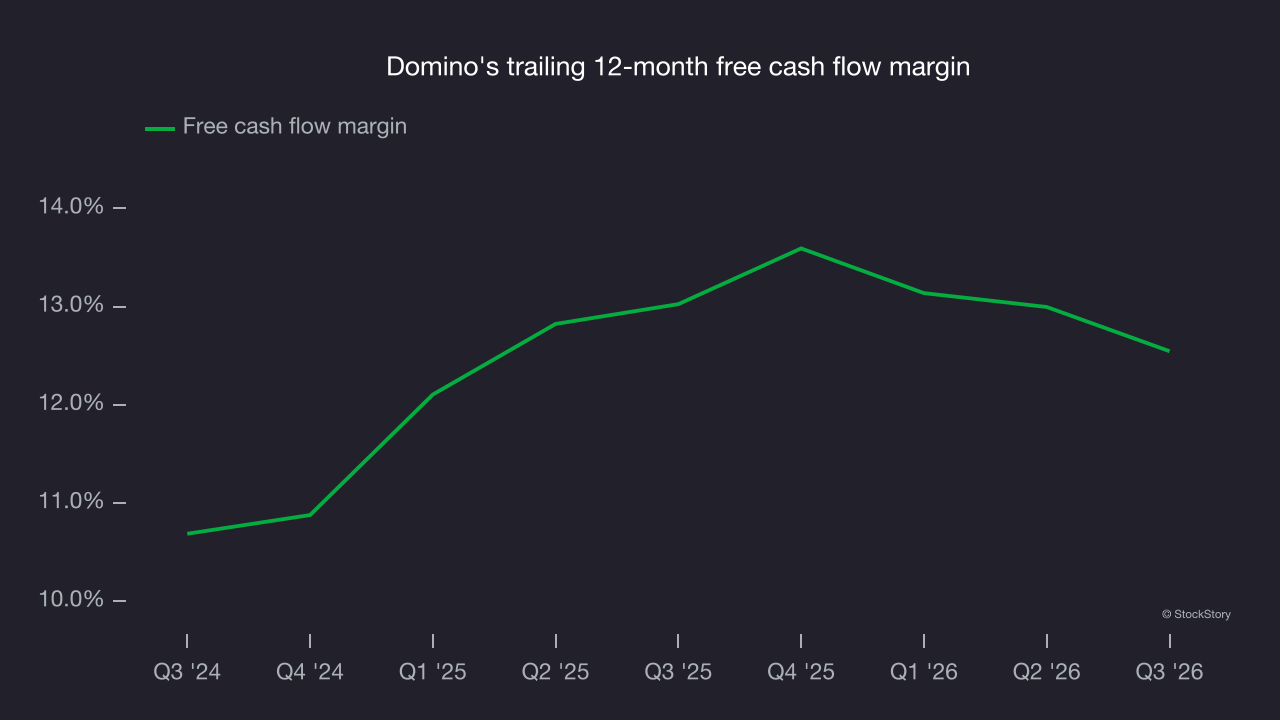
3. Free cash flow margin stuck in neutral
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
As you can see below, Domino’s margin was unchanged over the last year, showing it couldn’t improve. Its free cash flow margin for the trailing 12 months was 12.5%.
Final judgment
Domino's isn’t a terrible business, but it isn’t one of our picks. That said, the stock currently trades at 15.8× forward P/E (or $339.86 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better stocks to buy right now. We’d recommend looking at the Amazon and PayPal of Latin America.
Stocks we would buy instead of Domino's
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.