Electronic equipment provider Vontier (NYSE: VNT) reported Q3 2026 results beating Wall Street’s revenue expectations, but revenue fell by 2.1% year on year to $736.9 million. On the other hand, next quarter’s revenue guidance of $785 million was less impressive, coming in 1.5% below analysts’ consensus estimates. Its non-GAAP profit of $0.92 per share was 9.2% above analysts’ consensus estimates.
For more on Vontier, read our free full research report.
Vontier (VNT) Q3 2026 highlights:
- Revenue $736.9 million vs S&P analysts’ consensus estimates of $728.4 million (2.1% year-on-year decline, 1.2% beat)
- Adjusted EPS $0.92 vs S&P analysts’ consensus estimates of $0.84 (9.2% beat)
- Adjusted EBITDA $185.7 million vs analysts’ consensus estimates of $174.9 million (25.2% margin, 6.2% beat)
- Revenue guidance $785 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $797 million
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $3.62 at the midpoint, a 3.4% increase
- Operating margin 21.5%, up from 18.9% in the same quarter last year
- Free cash flow margin 16.6%, up from 12% in the same quarter last year
- Organic revenue rose 5.7% year on year (beat)
- Market capitalization $5.08 billion
"Vontier delivered a strong third quarter, with results exceeding our guidance across sales, margin, and EPS. Increasing adoption of our innovative products and solutions is contributing to above-market growth. Our simplification and 80/20 initiatives are delivering more meaningful operating leverage, with savings now tracking ahead of our original commitment. These dynamics are strengthening our earnings profile and give us the confidence to raise our full-year outlook," said Mark Morelli, President and Chief Executive Officer.
Revenue growth
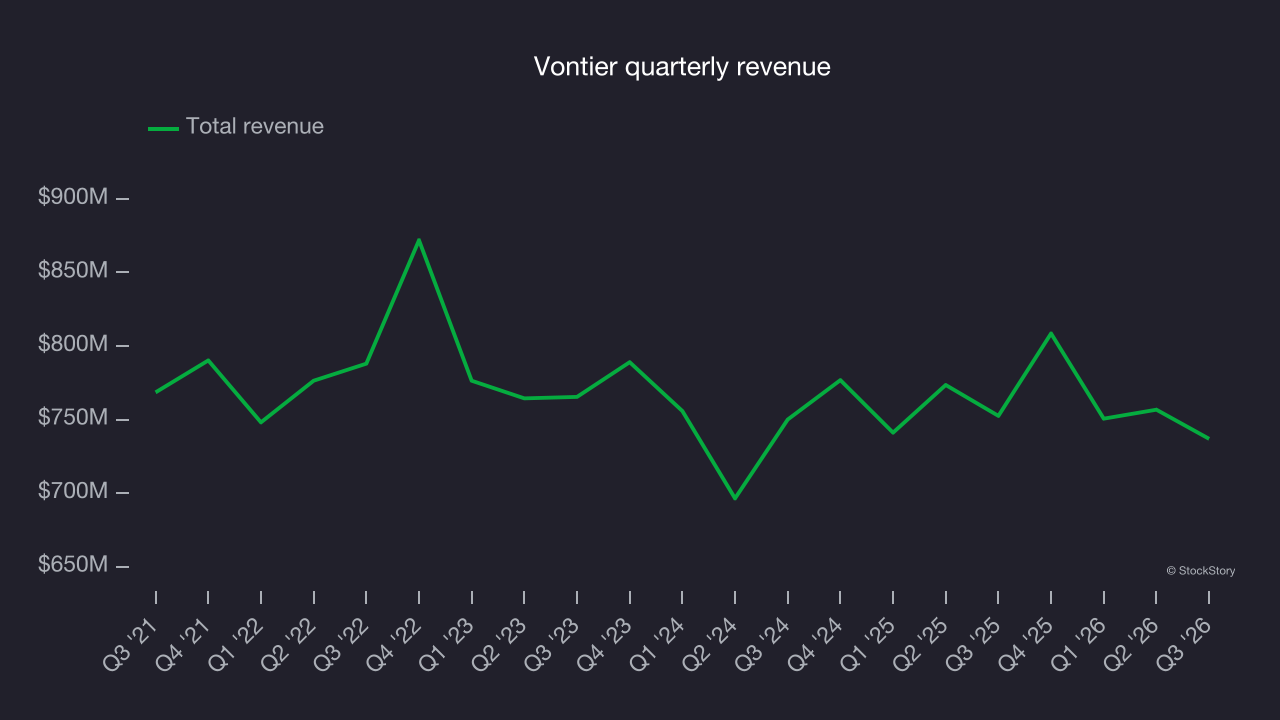
A company’s long-term revenue performance is one signal of its overall quality. Any business can report a good quarter or two, but the best consistently grow over the long haul. Vontier struggled to consistently increase demand as its $3.05 billion of revenue for the trailing 12 months was close to its revenue five years ago. This fell short of our standards and suggests it’s a lower-quality business.
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Vontier’s annualized revenue growth of 1% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 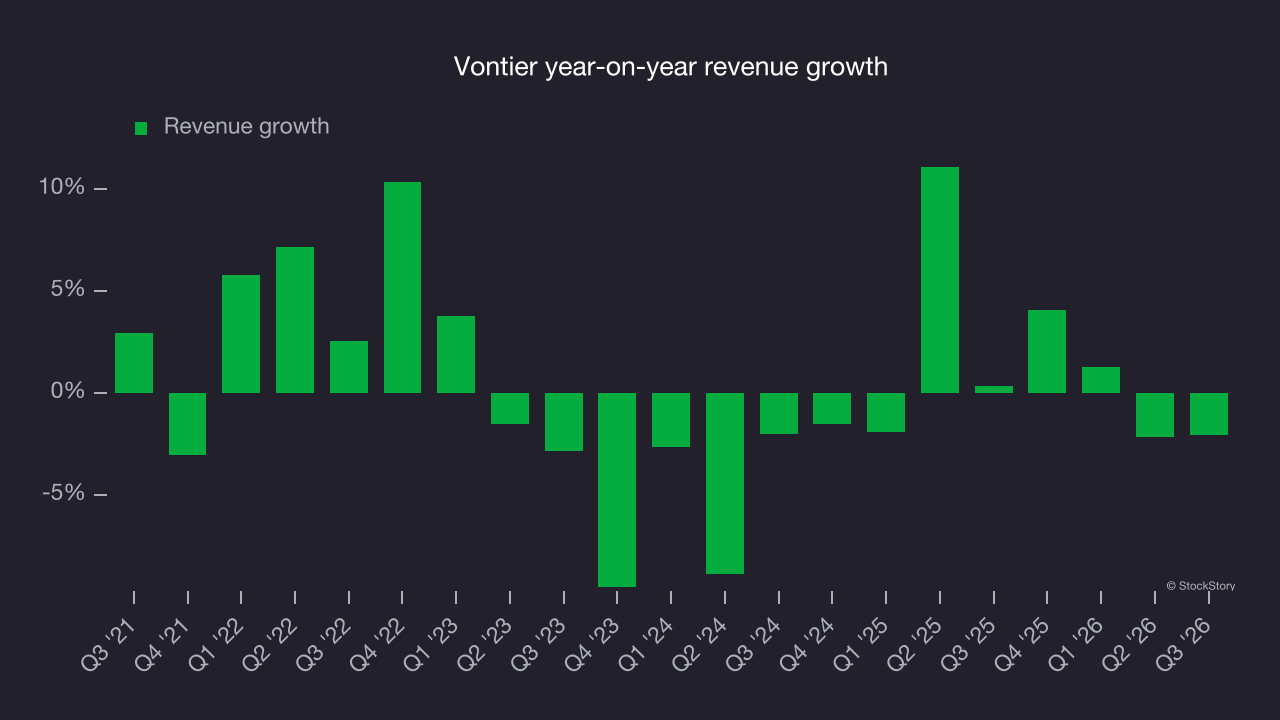
Organic revenue helps explain the company’s revenue dynamics by stripping out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Vontier’s organic revenue averaged 3.3% year-on-year growth. Organic growth outpaced its two-year revenue growth, indicating that some combination of divestitures and foreign exchange rates dampened its headline results. 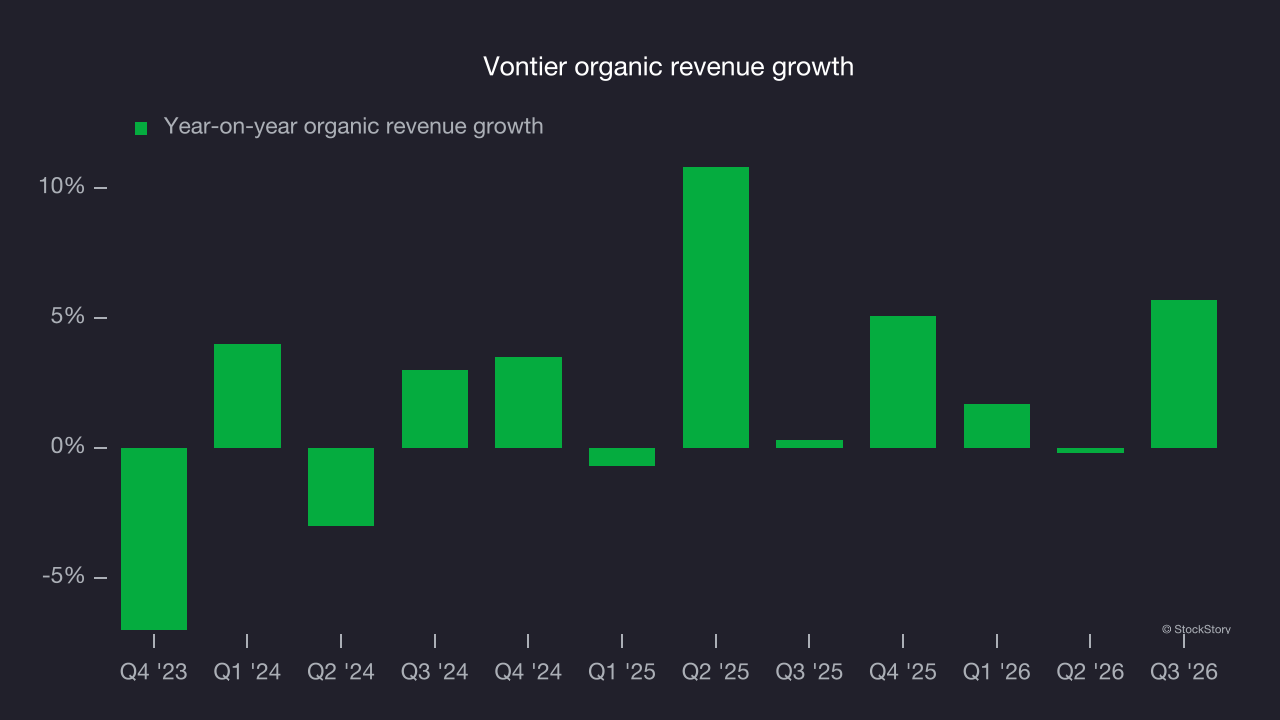
This quarter, Vontier’s revenue fell by 2.1% year on year to $736.9 million but beat Wall Street’s consensus estimates by 1.2%. Management is guiding for a 2.9% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P. This underwhelming projection suggests its products and services will face some demand headwinds.
Operating margin
Vontier’s operating margin has risen over the last 12 months and averaged 18.4% over the last five years. Its profitability was also strong for an industrials business thanks to its efficient cost structure and economies of scale. That outcome is unsurprising given its favorable gross margin baseline.
Analyzing the trend in its profitability, Vontier’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years, highlighting the consistency of its expense base.
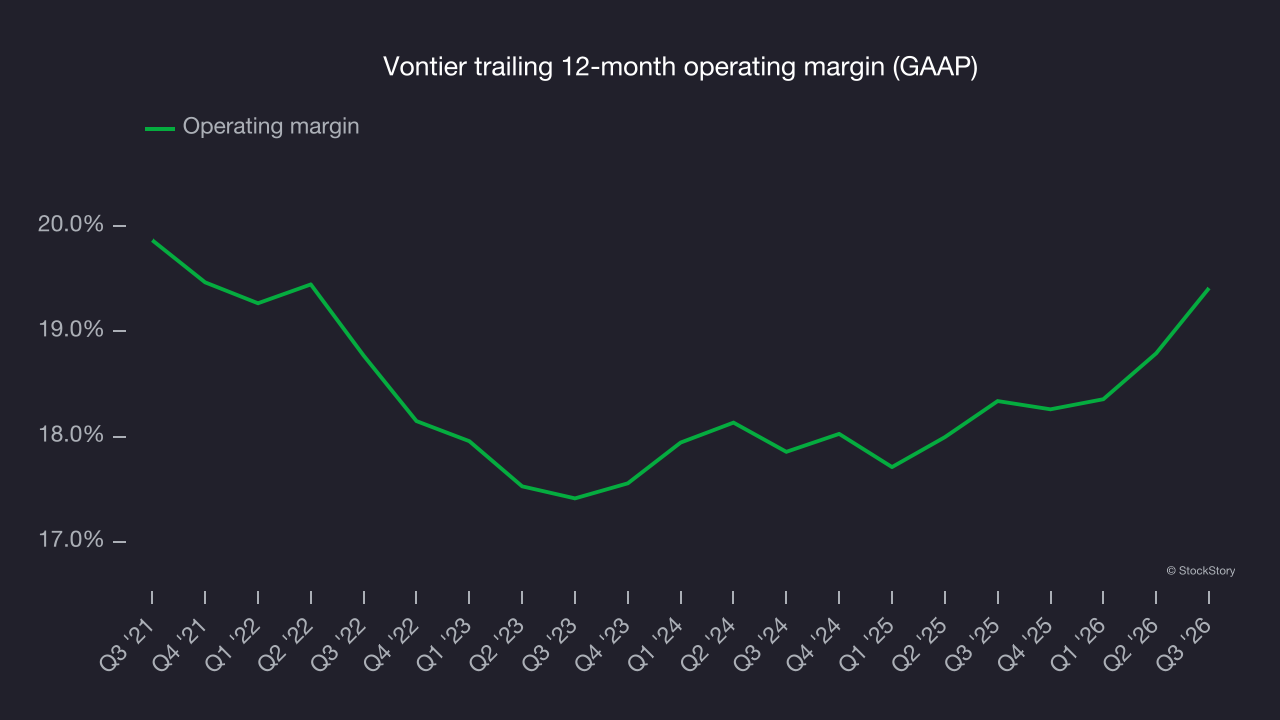
This quarter, Vontier generated an operating margin of 21.5%, up 2.6 percentage points year on year. Its gross margin expanded more than its operating margin, indicating that leverage on its cost of sales was the primary driver of the recent efficiency gains.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Vontier’s EPS grew at a 3.6% compounded annual growth rate over the last five years. This performance was better than its flat revenue but doesn’t tell us much about its business quality because its operating margin didn’t improve.
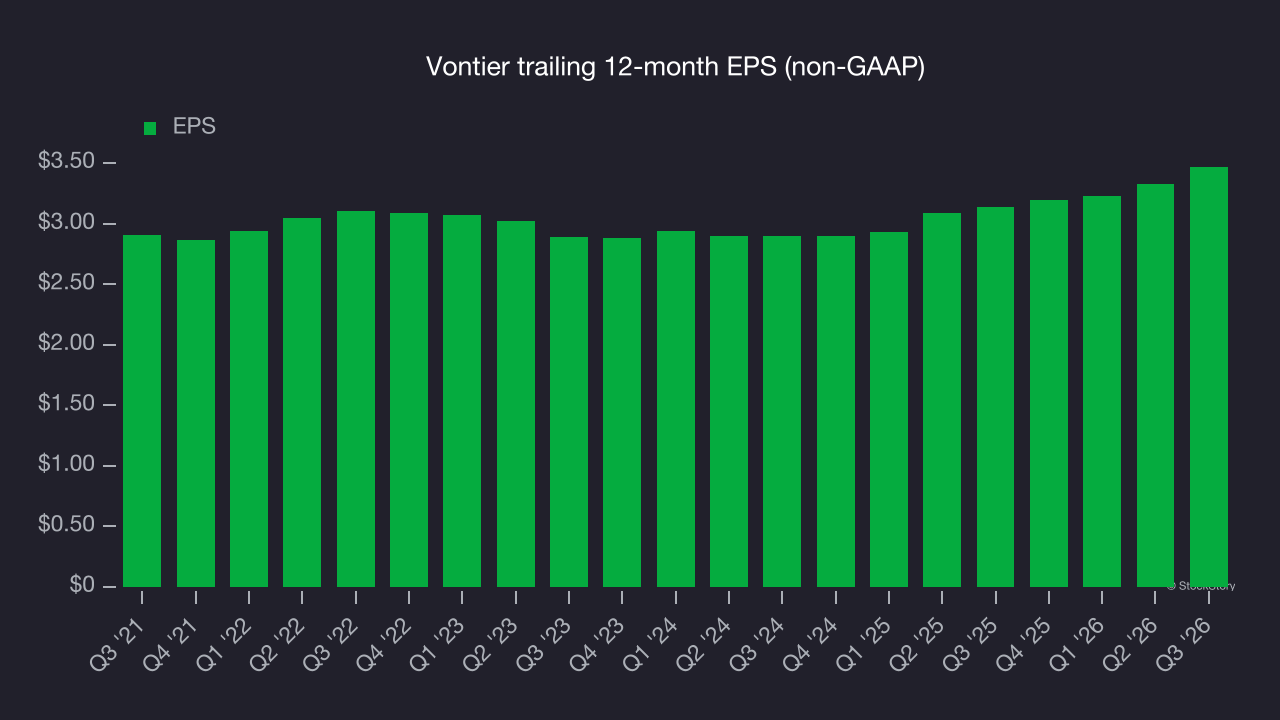
A closer look at Vontier’s earnings helps explain its performance. A five-year view shows that Vontier has repurchased its stock, shrinking its share count by 20.5%. Its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings. 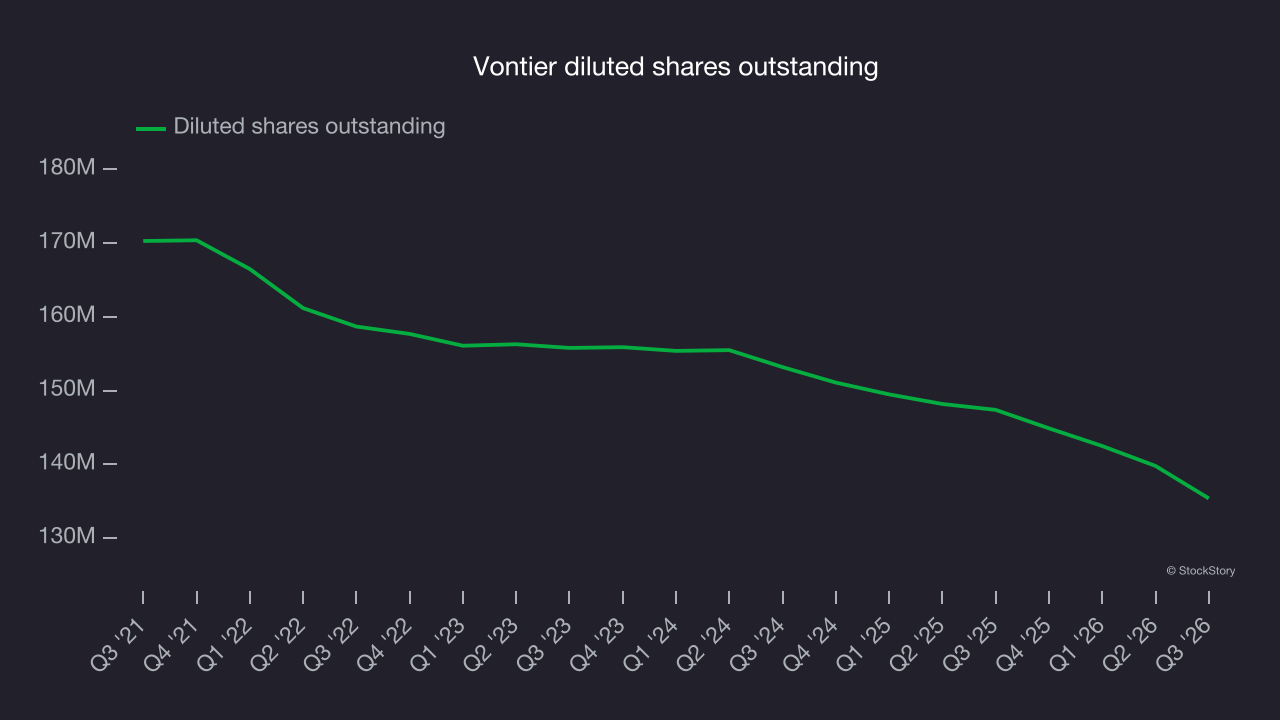
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Vontier, its two-year annual EPS growth of 9.4% was higher than its five-year trend. Accelerating earnings growth is almost always an encouraging data point.
In Q3, Vontier reported adjusted EPS of $0.92, up from $0.78 in the same quarter last year. This result beat analysts’ consensus estimates by 9.2%. Over the next 12 months, Wall Street expects Vontier’s full-year EPS to grow 6.1% from $3.47 to $3.68, according to S&P.
Key takeaways from Vontier’s Q3 results
Vontier paired full-year EPS guidance well above analysts’ consensus estimates with a weaker outlook for next quarter, when both EPS and revenue forecasts fell short of expectations. EBITDA also topped Wall Street’s consensus, giving this mixed quarter some key positives. Shares soared 11.3% to $41.82 immediately after the results.
Vontier may have had a good quarter, but that alone does not determine whether the stock is a buy. That decision should consider the bigger picture of valuation and business quality, as well as the latest earnings. Read our full research report here (it’s free).