RV manufacturer Thor Industries (NYSE: THO) reported revenue ahead of Wall Street’s expectations in Q2 CY2026, but sales fell by 8.4% year on year to $2.31 billion. Its GAAP profit of $0.78 per share was 15.9% below analysts’ consensus estimates.
Is now the time to buy THOR Industries? Find out by accessing our full research report, it’s free.
THOR Industries (THO) Q2 CY2026 Highlights:
- Revenue: $2.31 billion vs analyst estimates of $2.18 billion (8.4% year-on-year decline, 6.1% beat)
- EPS (GAAP): $0.78 vs analyst expectations of $0.93 (15.9% miss)
- Adjusted EBITDA: $131.7 million vs analyst estimates of $138.7 million (5.7% margin, 5% miss)
- Operating Margin: 3.4%, in line with the same quarter last year
- Market Capitalization: $3.64 billion
"Our earnings performance did not keep pace with our top-line performance. As the fiscal year progressed, heightened affordability concerns and increasing material costs resulted in significant pressure on our gross margins. We responded with restructuring actions and began evolving our North American RV operating model. We directed those initiatives towards protecting attainable price points for consumers, accepting near-term margin pressure in exchange for long-term health of the business. The strength of our brands, the health of our balance sheet and our leadership across the RV market remain firmly intact and we are using this cycle to build a permanently stronger THOR," stated Martin.
Company Overview
Created through the acquisition and merger of various RV manufacturers, THOR Industries manufactures and sells a range of recreational vehicles, including motorhomes and travel trailers, catering to consumers seeking the freedom and comfort of the RV lifestyle.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. THOR Industries’s demand was weak over the last five years as its sales fell at a 4.8% annual rate. This wasn’t a great result and is a sign of poor business quality.
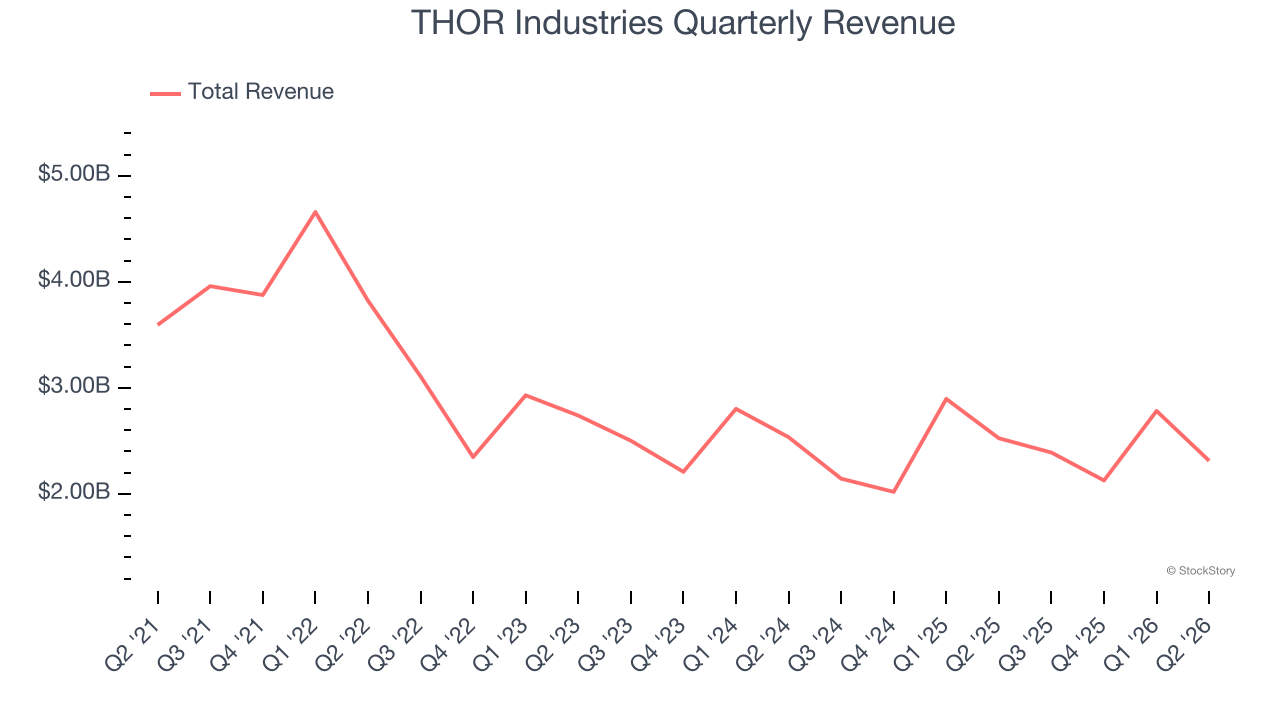
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. THOR Industries’s annualized revenue declines of 2.2% over the last two years suggest its demand continued shrinking. 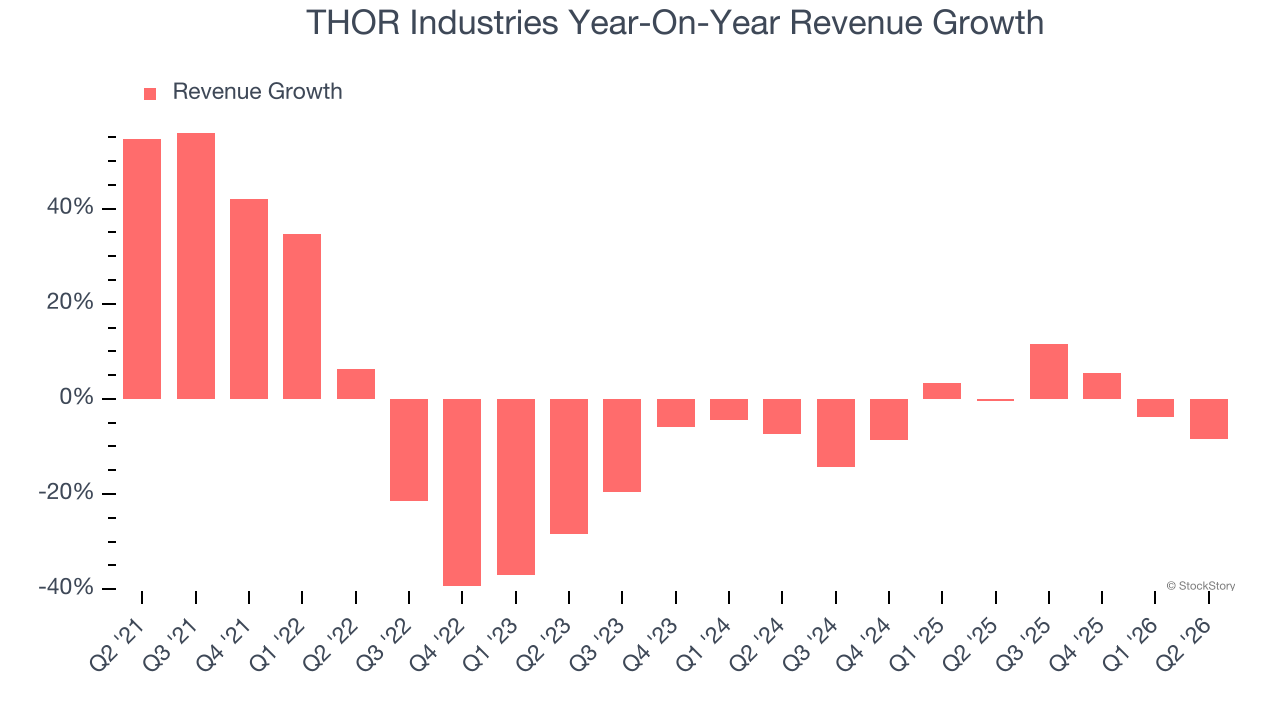
This quarter, THOR Industries’s revenue fell by 8.4% year on year to $2.31 billion but beat Wall Street’s estimates by 6.1%.
Looking ahead, sell-side analysts expect revenue to grow 1.4% over the next 12 months. While this projection indicates its newer products and services will fuel better top-line performance, it is still below average for the sector.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Operating Margin
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
THOR Industries was profitable over the last five years but held back by its large cost base. Its average operating margin of 5.4% was weak for an industrials business. This result isn’t too surprising given its low gross margin as a starting point.
Analyzing the trend in its profitability, THOR Industries’s operating margin decreased by 7 percentage points over the last five years. THOR Industries’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers.
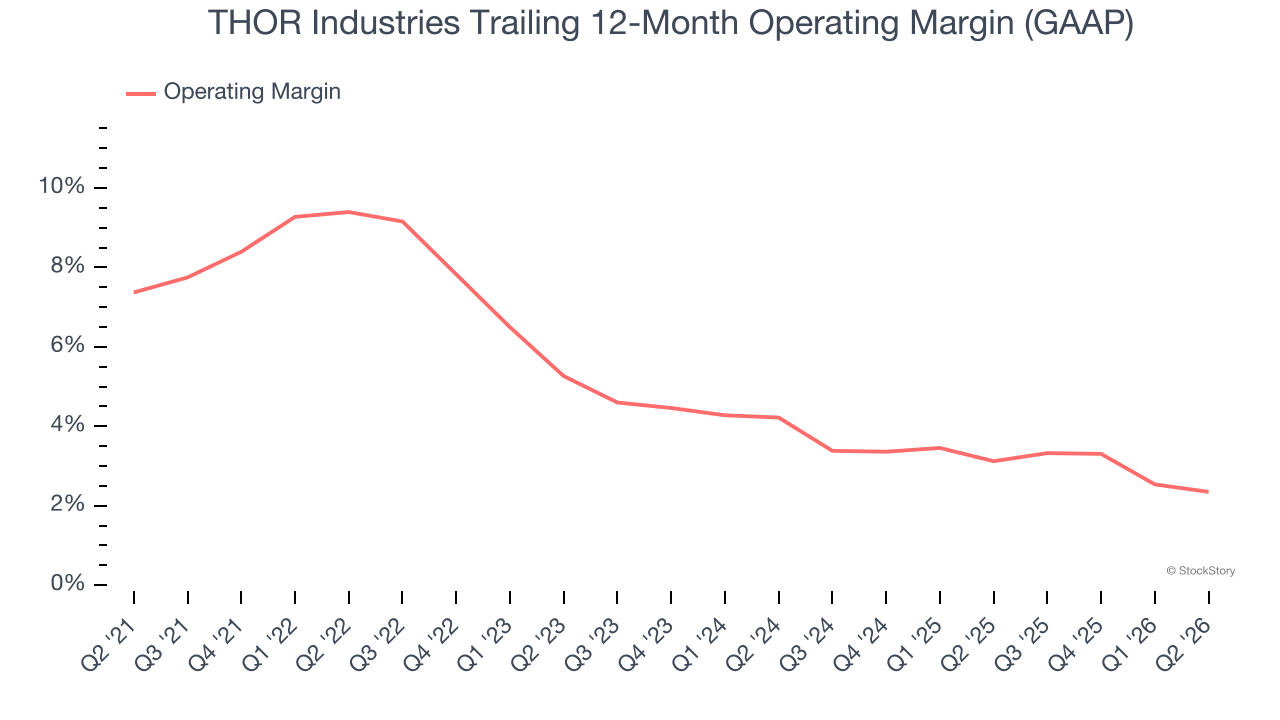
This quarter, THOR Industries generated an operating margin profit margin of 3.4%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Sadly for THOR Industries, its EPS declined by 22.2% annually over the last five years, more than its revenue. This tells us the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
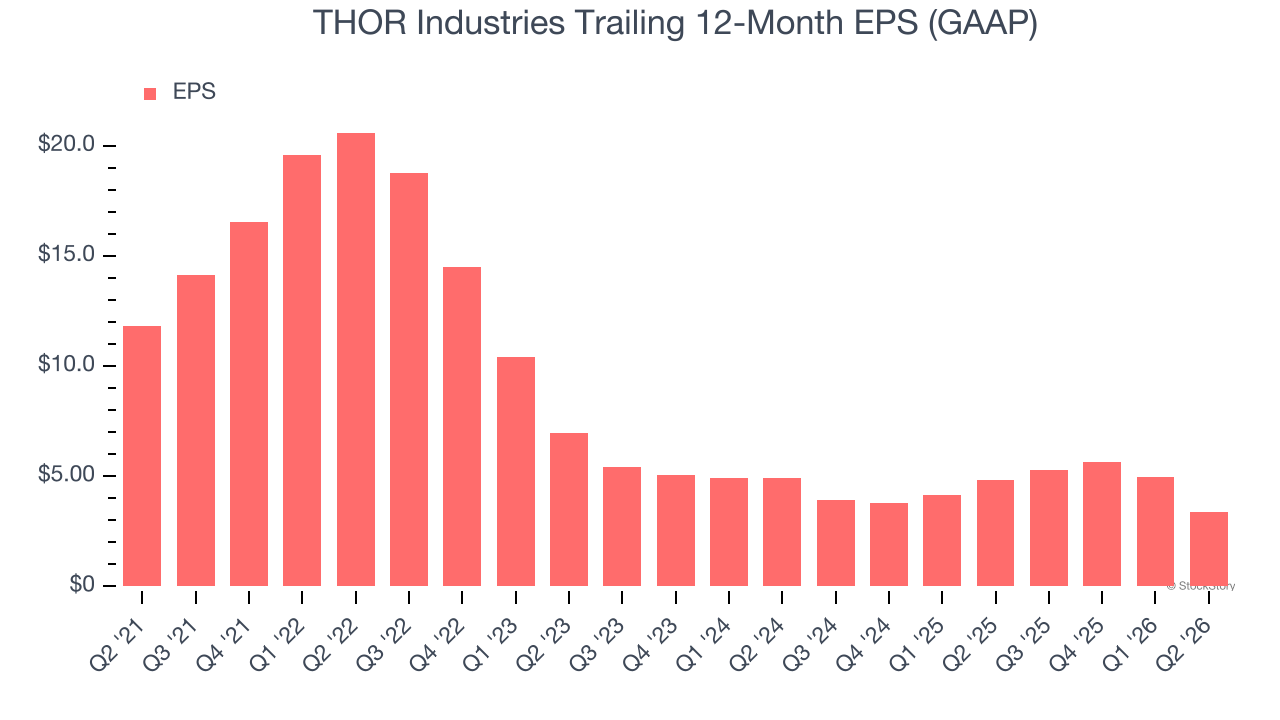
We can take a deeper look into THOR Industries’s earnings to better understand the drivers of its performance. As we mentioned earlier, THOR Industries’s operating margin was flat this quarter but declined by 7 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For THOR Industries, its two-year annual EPS declines of 17.3% show it’s still underperforming. These results were bad no matter how you slice the data.
In Q2, THOR Industries reported EPS of $0.78, down from $2.36 in the same quarter last year. This print missed analysts’ estimates. Over the next 12 months, Wall Street expects THOR Industries’s full-year EPS to grow 26.8% from $3.38 to $4.29.
Key Takeaways from THOR Industries’s Q2 Results
We were impressed by how significantly THOR Industries blew past analysts’ revenue expectations this quarter. On the other hand, its EBITDA missed and its EPS fell short of Wall Street’s estimates. Overall, this was a softer quarter. The stock traded up 1.8% to $71.21 immediately after reporting.
So should you invest in THOR Industries right now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).