Gulfport Energy’s stock price has taken a beating over the past six months, shedding 29.1% of its value and falling to $152.28 per share. This may have investors wondering how to approach the situation.
Given the weaker price action, is now a good time to buy GPOR? Find out in our full research report, it’s free.
Why Does Gulfport Energy Spark Debate?
With drilling operations focused on the Utica Shale in eastern Ohio and the SCOOP play in central Oklahoma, Gulfport Energy (NYSE: GPOR) drills for and produces natural gas from underground shale formations.
Two Positive Attributes:
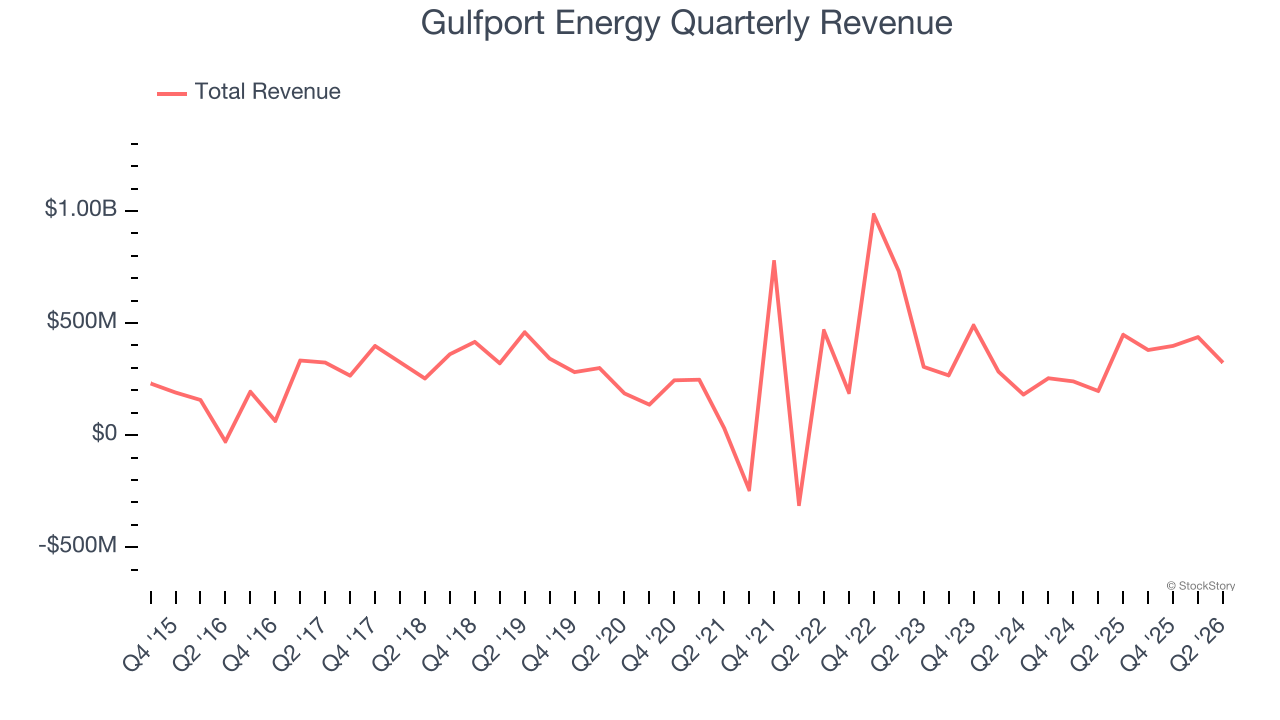
1. Skyrocketing Revenue Shows Strong Momentum
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can shine for a year or so, but a top-tier one should exhibit resilience through cycles. Thankfully, Gulfport Energy’s 18.5% annualized revenue growth over the last five years was impressive. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
2. Elite Gross Margin Powers Best-In-Class Business Model
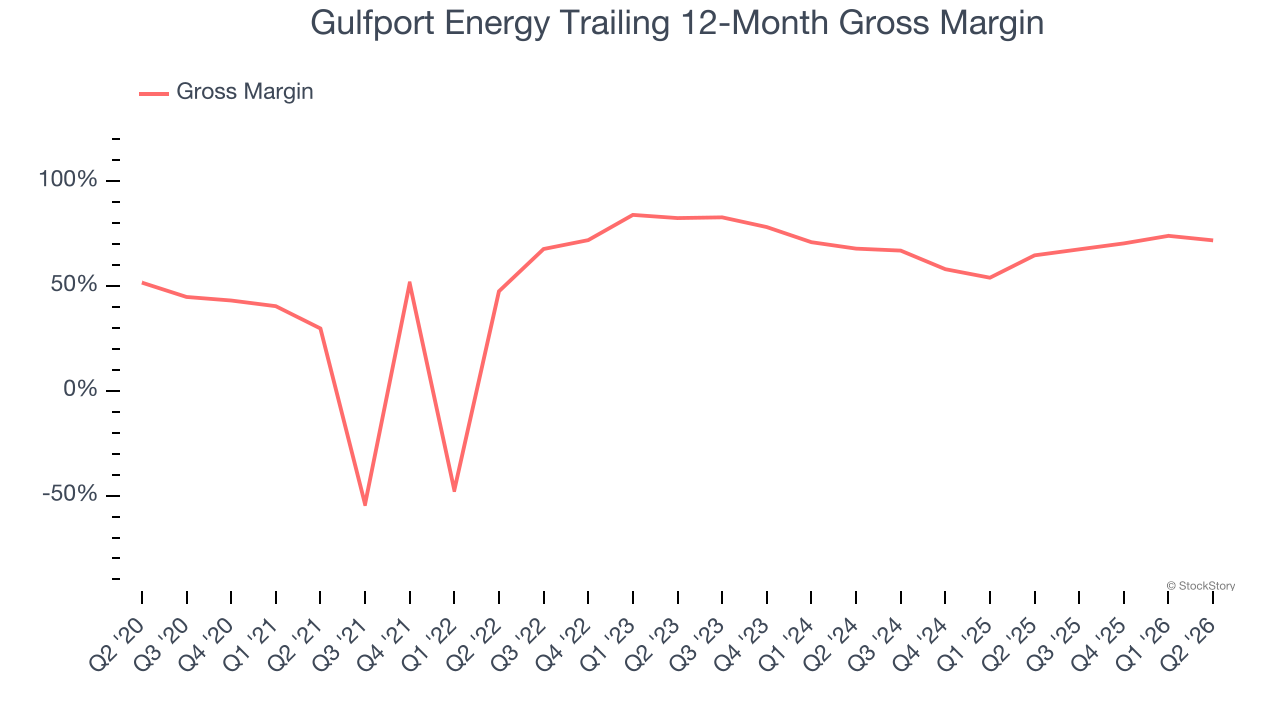
In a single quarter or year, gross margins in the sector can swing wildly due to commodity prices, hedging, or changes in labor costs. Over a multi-year period across different points in the cycle, gross margin differences can signal whether a company is a structurally-advantaged producer (“rock” quality, takeaway, operating costs) or not.
Gulfport Energy, which averaged 70.9% gross margin over the last five years, exhibits impressive unit economics in the sector. It means the company will remain profitable at lower commodity prices than peers with inferior gross margins and serves as an excellent starting point for ultimate operating profits and free cash flow generation.
One Reason to Be Careful:
Shrinking EBITDA Margin
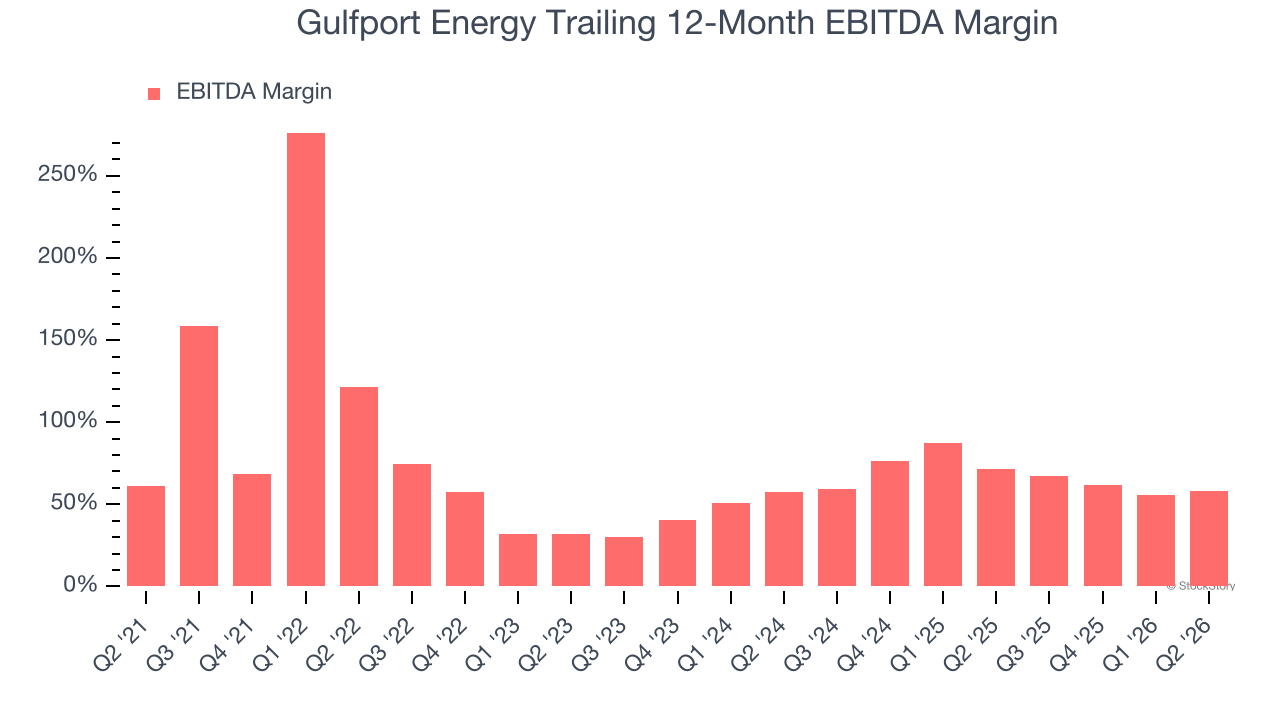
Adjusted EBITDA margin strips out accounting distortions tied to depletion and historical drilling spend, providing a clearer view of the cash-generating power of the underlying asset base before financing and reinvestment decisions.
Analyzing the trend in its profitability, Gulfport Energy’s EBITDA margin decreased by 63.6 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its EBITDA margin for the trailing 12 months was 57.9%.
Final Judgment
Gulfport Energy has huge potential even though it has some open questions. After the recent drawdown, the stock trades at 6.2× forward P/E (or $152.28 per share). Is now the right time to buy? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.